
Student Debt Relief
By Article Posted by Staff Contributor
The estimated reading time for this post is 341 seconds
The Biden-Harris Administration has proposed a comprehensive student debt relief plan that aims to alleviate the burden of student loan debt on millions of Americans.
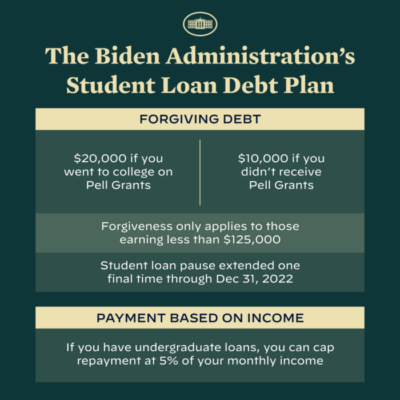
The plan includes measures such as expanding Public Service Loan Forgiveness (PSLF), cancelling up to $10,000 in student debt per borrower, and providing debt relief for borrowers who attended predatory for-profit institutions.
However, the plan has faced opposition from various quarters, including the Supreme Court of the United States (SCOTUS), which could potentially strike down student debt relief, and the Grand Old Party (GOP), whose debt ceiling plan puts student debt relief in jeopardy.
In this article, we will examine the Biden-Harris Administration student debt relief plan and the PSLF program, their potential impact on borrowers, and the challenges that lie ahead in their implementation.
The Biden-Harris Administration Student Debt Relief Plan
The Biden-Harris Administration’s student debt relief plan seeks to address the growing crisis of student loan debt in the United States, which currently stands at a staggering $1.7 trillion. The plan aims to provide relief to borrowers by cancelling some of their debt and expanding existing loan forgiveness programs.
Under the plan, the administration has proposed to cancel up to $10,000 in student debt per borrower. This would provide immediate relief to millions of borrowers who are struggling to make their monthly payments.
The administration has also proposed to provide debt relief for borrowers who attended predatory for-profit institutions that engaged in fraudulent or deceptive practices.
In addition to these measures, the administration has proposed to expand the PSLF program, which currently allows borrowers who work in public service jobs to have their loans forgiven after making 120 qualifying payments. The proposed expansion would make the program available to more borrowers and simplify the application process.
PSLF Program
The PSLF program was created in 2007 to incentivize borrowers to enter and remain in public service jobs.
Under the program, borrowers who work in public service jobs, such as teachers, nurses, and government employees, can have their loans forgiven after making 120 qualifying payments while working full-time for a qualifying employer.
The PSLF program has been a lifeline for many borrowers who have taken on significant amounts of student loan debt to pursue careers in public service. However, the program has faced numerous challenges, including high denial rates and a complex application process.
One of the main issues with the PSLF program is that it is difficult to navigate. Borrowers must meet a number of requirements to qualify for loan forgiveness, including making qualifying payments while working full-time for a qualifying employer.
This can be challenging for borrowers who are not familiar with the program’s requirements or who work in jobs that do not qualify.
Another issue with the program is that many borrowers have been denied loan forgiveness.
According to a report from the Government Accountability Office, only 1% of borrowers who applied for loan forgiveness under the PSLF program were approved as of December 2020.
The high denial rate has been attributed to a variety of factors, including unclear program requirements and insufficient guidance from loan servicers.
Despite these challenges, the PSLF program remains an important tool for borrowers who are pursuing careers in public service. The proposed expansion of the program under the Biden-Harris Administration’s student debt relief plan could make it more accessible to more borrowers and simplify the application process.
Potential Impact on Borrowers
The Biden-Harris Administration’s student debt relief plan and the proposed expansion of the PSLF program could have a significant impact on borrowers who are struggling with student loan debt.
The cancellation of up to $10,000 in student debt per borrower would provide immediate relief to millions of borrowers and make it easier for them to make their monthly payments.
The debt relief for borrowers who attended predatory for-profit institutions could also be a game-changer for these borrowers, who often face high levels of debt and limited job prospects.
The expansion of the PSLF program could also provide much-needed relief to borrowers who are pursuing careers in public service and struggling to make their loan payments.
However, the impact of these measures is likely to be limited in the face of the broader student loan debt crisis. While cancelling up to $10,000 in student debt per borrower would provide relief to some, it would not address the underlying issue of the rising cost of higher education and the increasing burden of student loan debt on borrowers.
Furthermore, the proposed expansion of the PSLF program may not be sufficient to address the challenges that borrowers currently face in accessing loan forgiveness.
While simplifying the application process and making the program more accessible is a step in the right direction, more needs to be done to ensure that borrowers are aware of the program and understand its requirements.
Challenges in Implementation
The implementation of the Biden-Harris Administration’s student debt relief plan and the proposed expansion of the PSLF program is likely to face significant challenges. One of the biggest challenges is the potential for legal challenges to the plan, including from the SCOTUS.
The SCOTUS recently heard arguments in a case involving a group of borrowers who are seeking loan forgiveness under the PSLF program.
The case centers on the question of whether borrowers who have made payments under income-driven repayment plans are eligible for loan forgiveness under the PSLF program.
If the SCOTUS rules against the borrowers, it could have significant implications for the PSLF program and the Biden-Harris Administration’s student debt relief plan.
It could also create uncertainty for borrowers who are currently making payments under income-driven repayment plans and relying on the PSLF program for loan forgiveness.
Another challenge in implementing the student debt relief plan is the potential for political opposition, particularly from the GOP.
The GOP has opposed the plan and has proposed a debt ceiling plan that would limit the amount of money the government can borrow and potentially jeopardize the student debt relief measures.
The GOP’s opposition to the plan could make it more difficult for the Biden-Harris Administration to pass the necessary legislation to implement the plan. It could also lead to a protracted political battle that could further delay relief for borrowers.
Conclusion
The Biden-Harris Administration’s student debt relief plan and the proposed expansion of the PSLF program have the potential to provide much-needed relief to millions of borrowers who are struggling with student loan debt. However, the plan faces significant challenges, including legal challenges and political opposition.
While the proposed measures would provide immediate relief to some borrowers, they do not address the broader issue of the rising cost of higher education and the increasing burden of student loan debt on borrowers.
More needs to be done to address these issues and ensure that borrowers have access to affordable higher education and a path to financial stability.


RELATED ARTICLES
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score. Learn how zero-balance accounts, credit utilization, and installment loans affect your FICO score—and why financial progress matters more than maximizing every point.
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the right reasons doesn't guarantee financial success. Explore how interest, hidden fees, limited savings, and unequal homeownership opportunities can turn supposedly good debt into a lasting...
1 Comment
Leave Comment
Cancel reply
Gig Economy
American Middle Class / Oct 23, 2026
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score. Learn how zero-balance accounts, credit utilization, and installment loans affect your...
By Article Posted by Staff Contributor
American Middle Class / Oct 22, 2026
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the right reasons doesn't guarantee financial success. Explore how interest, hidden fees,...
By MacKenzy Pierre
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From Florida's homestead exemptions to Massachusetts zoning reform and California's affordable housing...
By Article Posted by Staff Contributor
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover how new rules from federal housing regulators could affect mortgage approvals,...
By Article Posted by Staff Contributor
American Middle Class / Oct 13, 2026
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what something actually costs. From buy now, pay later services to longer...
By Article Posted by Staff Contributor
American Middle Class / Oct 12, 2026
Fair Capitalism: We Don’t Need to Abolish Capitalism. We Need to Fix It.
Fair capitalism means preserving entrepreneurship and profits while ensuring working Americans share more meaningfully in the prosperity they help create.
By MacKenzy Pierre
American Middle Class / Oct 12, 2026
The Sunday Scaries: How Financial Independence Can Help You Reclaim Your Weekend
The Sunday Scaries can begin long before Monday morning. Building emergency savings, lowering monthly expenses, and increasing financial independence may help you reclaim your weekend.
By Article Posted by Staff Contributor
Business / Aug 08, 2026
The Missing Middle in Black Entrepreneurship
Black entrepreneurship has expanded dramatically. The next challenge is helping more Black-owned businesses move from self-employment to employer firms and sustainable scale.
By FMC Editorial Team
Personal Finance / Aug 01, 2026
Cash Strategy: Put Every Dollar in the Right Place
Your checking account, emergency fund, short-term savings, and investments should not be managed the same way. This cash strategy helps assign every dollar to the right...
By Article Posted by Staff Contributor
Personal Finance / Aug 01, 2026
Best HYSA: How to Choose Beyond the Highest APY
A competitive interest rate matters, but it is only one part of choosing a high-yield savings account. Compare insurance, fees, access, transfer speed, and promotional conditions.
By Article Posted by Staff Contributor
Latest Reviews
American Middle Class / Oct 23, 2026
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score....
American Middle Class / Oct 22, 2026
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the...
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From...
Pingback: Americans of all Generations Living Paycheck to Paycheck - FMC