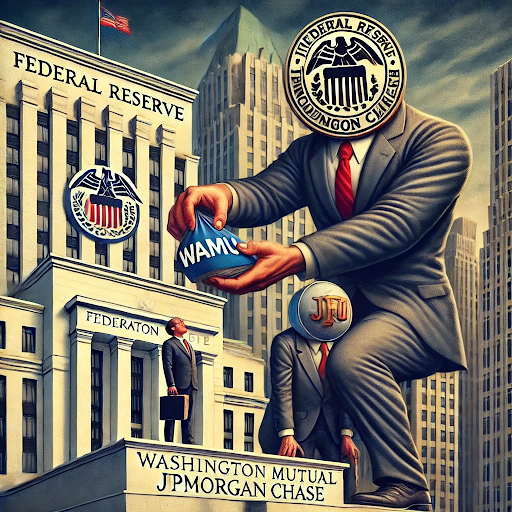
Washington Mutual, once the largest savings and loan association in the United States, became infamous for its dramatic collapse in 2008.
The downfall of this financial giant is a stark reminder of the importance of vigilance and awareness in financial matters.
This article explores the background, key events, and outcomes of the Washington Mutual scandal, highlighting red flags and offering practical advice on recognizing and reporting similar scams.
Background
Washington Mutual, known as WaMu, was established in 1889 in Seattle, Washington. Over the decades, it grew into a significant financial institution, primarily offering banking and mortgage services. By the early 2000s, WaMu had expanded rapidly, acquiring numerous other banks and mortgage companies.
Key Events Leading to the Collapse of Washington Mutual
Subprime Mortgage Crisis
In the early 2000s, Washington Mutual (WaMu) aggressively pursued the subprime mortgage market, targeting high-risk borrowers. These borrowers often had lower credit scores, making them less likely to qualify for conventional loans.
WaMu offered adjustable-rate mortgages (ARMs) to attract these customers, who initially had low interest rates but would reset to higher rates after a few years.
Statistics:
- By 2006, WaMu had issued $33 billion in subprime loans.
- Approximately 50% of WaMu’s mortgage portfolio consisted of subprime loans.
- From 2003 to 2006, WaMu’s subprime mortgage volume increased by 450%.
Risky Lending Practices
A high tolerance for risk characterized WaMu’s lending practices. The bank implemented programs that allowed for minimal documentation from borrowers, high loan-to-value (LTV) ratios, and interest-only payment options.
These practices contributed significantly to the surge in loan defaults and foreclosures, as borrowers often could not meet the repayment terms once interest rates were adjusted.
Statistics:
- WaMu’s Option Adjustable-Rate Mortgages (ARMs) accounted for 47% of its mortgage portfolio by 2007.
- The default rate for WaMu’s subprime loans reached nearly 20% by the end of 2008.
- WaMu’s high-LTV loans, where the loan amount was close to or exceeded the value of the property, accounted for over 40% of its mortgage portfolio.
Regulatory Red Flags
Throughout the early 2000s, internal and external auditors and regulators raised numerous red flags about WaMu’s lending practices. These warnings highlighted the bank’s exposure to high-risk loans and the potential for significant financial instability.
Despite these warnings, WaMu’s leadership often ignored or downplayed the risks, continuing their aggressive lending strategies.
Statistics:
- In 2003, the Office of Thrift Supervision (OTS) cited WaMu for risk management and loan documentation deficiencies.
- By 2008, WaMu faced over 500 regulatory violations related to mortgage lending practices.
- The OTS issued multiple cease-and-desist orders to WaMu between 2003 and 2008, which the bank’s executives largely disregarded.
Bank Run and FDIC Seizure
As the subprime mortgage crisis unfolded and WaMu’s financial stability deteriorated, confidence in the bank eroded. In September 2008, amid the broader financial crisis, customers began withdrawing their deposits en masse, leading to a severe liquidity crisis.
Statistics:
- Between September 15 and September 25, 2008, WaMu customers withdrew $16.7 billion in deposits.
- By September 25, 2008, WaMu’s total deposits had fallen from $188 billion to $143 billion.
- The FDIC seized WaMu’s assets, marking the largest bank failure in U.S. history. At the time of the seizure, WaMu held $307 billion in assets.
Outcomes
- Acquisition by JPMorgan Chase: Following the FDIC seizure, WaMu’s banking operations were sold to JPMorgan Chase for $1.9 billion. This acquisition helped stabilize the banking system but resulted in significant losses for WaMu’s shareholders and employees.
- Legal Repercussions: Several former executives of WaMu faced legal action. Kerry Killinger, the former CEO, and other top executives were accused of reckless management and misleading investors. However, many of the lawsuits were settled without admitting wrongdoing.
- Impact on Financial Regulations: The collapse of WaMu and other financial scandals led to significant changes in financial regulation. The Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010 aimed to prevent such crises by increasing oversight and improving transparency in the financial industry.
Recognizing and Reporting Financial Scams
Red Flags to Watch For
- Aggressive Sales Tactics: Be wary of high-pressure sales tactics, especially those promising guaranteed returns with little risk.
- Lack of Transparency: Financial institutions should provide clear, detailed information about their products and services. Be cautious if you encounter vague or confusing terms.
- Unusual Account Activity: Monitor your financial accounts regularly for unusual or unauthorized transactions.
- Too Good to Be True: If an investment opportunity seems too good to be true, it probably is. Always conduct thorough research and seek professional advice.
How to Report Suspected Scams
- Contact Authorities: Report suspected financial scams to regulatory authorities such as the Securities and Exchange Commission (SEC) or the Consumer Financial Protection Bureau (CFPB).
- Notify Your Bank: If you suspect fraudulent activity in your account, contact your bank or financial institution immediately.
- Seek Legal Advice: Consult with a legal professional to understand your rights and the appropriate actions.
Conclusion
The Washington Mutual scandal is a powerful reminder of the risks inherent in the financial world.
By staying informed, vigilant, and proactive, individuals can protect themselves from similar scams and contribute to a more stable and transparent financial system.