
From FDR’s 30-Year Breakthrough to Trump’s 50-Year Pitch: Is This Still About Homeownership — or Just Smaller Payments?
By Article Posted by Staff Contributor
The estimated reading time for this post is 375 seconds
In the 1930s, Franklin D. Roosevelt’s team looked at a housing market full of short, risky mortgages and said: we’re going to redesign this so regular people can actually buy and keep a house. That’s how we got the long, fixed, fully amortizing mortgage the U.S. is famous for — first through FHA in 1934, then scaled through Fannie Mae in 1938. That model — long term, low-ish down, predictable payment — is what eventually became the “American” 30-year mortgage.
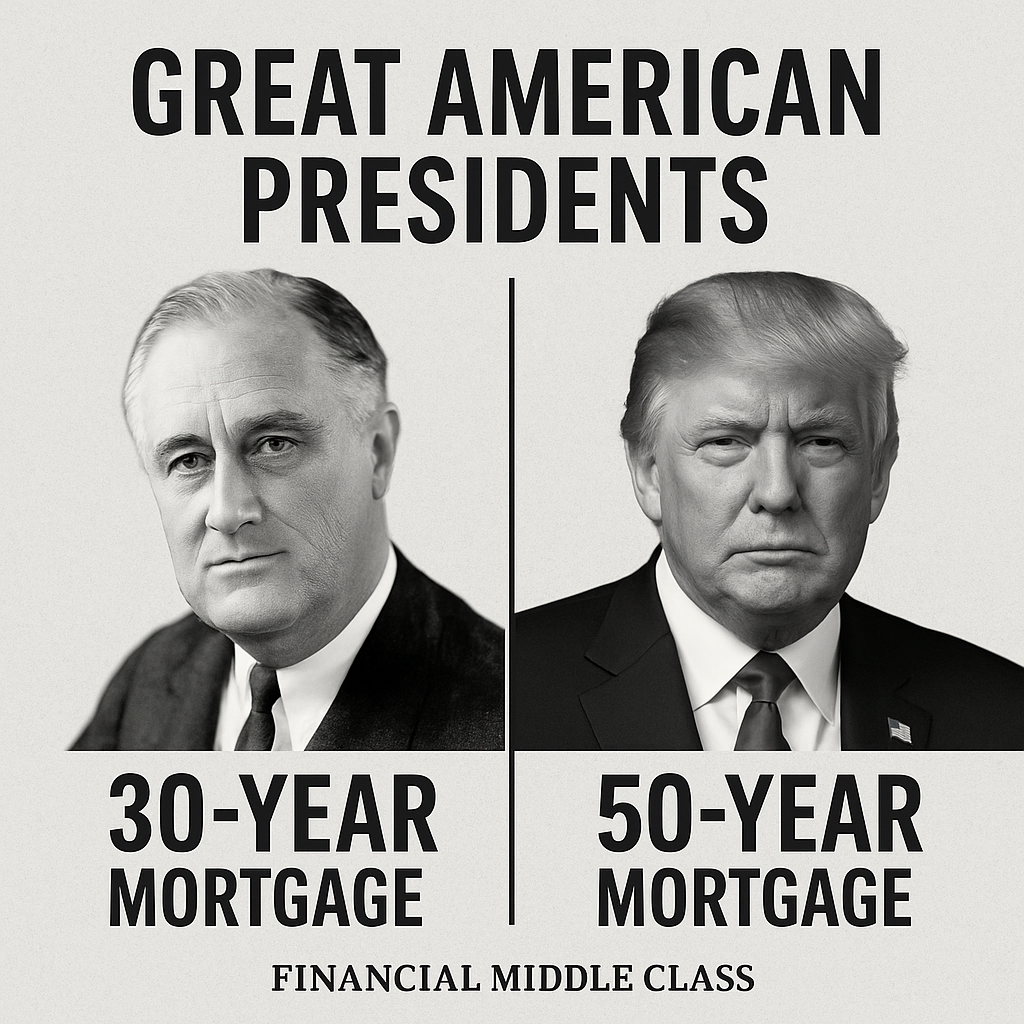
Now fast-forward to 2025. Housing is expensive, rates are still north of 6%, supply is thin, and first-time buyers are squeezed. Into that moment, Donald Trump floated the idea of a 50-year mortgage — framing it alongside FDR in a Truth Social post that put Roosevelt under “30-Year Mortgage” and himself under “50-Year Mortgage,” signaling: he did it for his time, I’ll do it for mine. Coverage of the idea made it clear this is something his camp is “considering” as a way to make payments smaller in a high-price market.
Before FDR: Housing Was a Cash Sport
Pre-New Deal mortgages looked nothing like today:
- Terms were short — 3 to 5 years was normal.
- Down payments were big — 40–50%.
- Many loans were interest-only with a balloon payment at the end.
- And if the bank wouldn’t refinance when the balloon hit (hello, Great Depression), you lost the house.
In other words, the system favored people with cash, not people with steady income. That’s the problem the New Deal housing agencies were built to fix.
What FDR Actually Did
Roosevelt’s housing moves didn’t just “help” borrowers — they standardized a safer mortgage:
- FHA (1934) insured long-term, fixed-rate, fully amortizing loans so lenders would actually make them. That’s the core design of what we still use.
- Fannie Mae (1938) created a secondary market so lenders could sell those FHA/VA-style loans and keep lending. That made the 30-year scalable.
- Post-WWII policy then made 30-year terms normal for new and existing homes.
FDR’s intent was stability and eventual ownership: take people off short, risky, balloon-type loans and put them on long, predictable, finishable mortgages.
Why the 30-Year Worked
The 30-year fixed caught on in the U.S. (unlike most of the world) because it balanced everyone’s needs:
- Borrowers got a payment they could plan around.
- The loan actually amortized — every month you owned a little more.
- Government insurance + a secondary market made it safe for lenders.
That mix is what helped push homeownership from the low-40% range mid-century to above 60%.
So: long mortgage → broader homeownership.
2025’s Problem Is Different
Today’s problem isn’t “mortgages are too risky.” It’s “houses cost $415,200 on median, rates are 6.22%, and that monthly is punching people in the mouth.” September 2025 NAR data shows the median existing-home price sitting right there at $415,200 — the 27th straight month of year-over-year price increases. At the same time, Freddie Mac put the 30-year fixed at 6.22% on November 6, 2025. That combo equals high payments.
So politicians go looking for a lever that doesn’t require building more homes, fixing zoning, or fighting NIMBYs. Easiest lever? Make the loan longer.
Trump’s 50-Year Pitch, in Plain English
The version being talked about now is exactly that: stretch the term from 30 to 50 so the monthly drops. Reporting on the idea framed it as a “shake-up to the housing market” — clearly meant to address affordability, not banking stability.
Here’s the thing, though: longer term = lower monthly and way, way more interest.
So let’s show it.
30-Year vs. 50-Year on a Median-Priced Home
Let’s use the real, current numbers:
- Price: $415,200 (NAR, Sept. 2025)
- Down: 20% → loan = $332,160
- Rate: 6.22% (Freddie Mac, Nov. 6, 2025)
I ran the standard mortgage math:
- 30-year payment (P&I): ≈ $2,039/mo
- 50-year payment (P&I): ≈ $1,803/mo
So yes — the 50-year saves you about $236/month.
But look at lifetime interest:
- 30-year total interest: ≈ $401,800
- 50-year total interest: ≈ $749,500
- Extra interest just for stretching: ≈ $347,700
Same house. Same rate. Just… 20 more years of paying the bank.
Median Home: 30-Year vs 50-Year
Assumes $415,200 price, 20% down, $332,160 loan, 6.22% rate.
| Metric | 30-Year | 50-Year |
|---|---|---|
| Monthly payment | ≈ $2,039 | ≈ $1,803 |
| Total interest paid | ≈ $401,800 | ≈ $749,500 |
| Length of debt | 30 years (360 payments) | 50 years (600 payments) |
| FMC takeaway | Stronger equity path | Cheaper monthly, weaker wealth |
Bottom line: you saved ~$236/month but paid ~$348,000 extra over the life of the loan.
© Financial Middle Class —
Now Do It for the Real Target: FHA Buyers
Let’s be honest — the people most likely to jump at a 50-year are the people already using FHA because they don’t have 20% down.
FHA in 2025 still lets you in with 3.5% down, still charges 1.75% upfront mortgage insurance (usually financed), and most borrowers in that range are paying around 0.55% annual MIP — sometimes more — and if you put less than 10% down, you pay MIP for the life of the loan.
So let’s run the same $415,200 house through the FHA machine:
- Price: $415,200
- Down: 3.5% → $14,532
- Base loan: $400,668
- 1.75% UFMIP financed → new loan ≈ $407,680
- Rate: 6.22%
- Annual MIP 0.55% → ≈ $187/mo
(Those MIP numbers line up with current 2025 FHA tables.)
Payments:
- 30-year FHA P&I ≈ $2,502
- MIP ≈ $187
- Total 30-year FHA payment ≈ $2,689/mo
- 50-year FHA P&I ≈ $2,213
- MIP ≈ $187
- Total 50-year FHA payment ≈ $2,399/mo
So the 50-year still saves about $290/month — a little more relief than the conventional example because the loan is bigger.
But now look at the lifetime cost:
- 30-year FHA interest ≈ $493,000
- 50-year FHA interest ≈ $920,000
- Extra interest = ≈ $427,000 more
- And because you put less than 10% down, that $187 FHA MIP sticks for the whole 50 years.
So… Is a 50-Year Mortgage a Good Idea?
“FDR’s 30-year mortgage brought people into ownership. A 50-year mortgage risks bringing people into permanent housing debt.”
A 50-year might help a household qualify in 2025, but it doesn’t help them build in 2035, 2045, 2055. And in a market where supply is still tight, giving buyers more payment room can just get captured in higher prices — which means the policy ends up helping sellers and builders more than the middle-income buyer we said we were trying to help.
FHA 3.5% Down: 30-Year vs 50-Year
Assumes $415,200 price, 3.5% down, UFMIP financed (1.75%), $407,680 loan, 6.22% rate, FHA annual MIP 0.55%.
| Metric | FHA 30-Year | FHA 50-Year |
|---|---|---|
| P&I payment | ≈ $2,502 | ≈ $2,213 |
| + FHA MIP | ≈ $187 | ≈ $187 |
| Total monthly | ≈ $2,689 | ≈ $2,399 |
| Lifetime interest (P&I) | ≈ $493,000 | ≈ $920,000 |
| MIP paid for… | Entire term (30 yrs) | Entire term (50 yrs) |
FMC takeaway: The 50-year FHA makes the monthly easier (~$290 less) but locks a first-time buyer into decades more interest and decades more mortgage insurance — classic payment relief, not wealth relief.
© Financial Middle Class —
What an FDR-Style 2025 Fix Would Actually Look Like
If we really wanted to honor the FDR comparison, we’d do things that strengthen the buyer’s balance sheet, not just lubricate the monthly:
- Build more — supply is the real affordability fix.
- Let more mortgages be assumable/portable so people with 3% pandemic loans can sell without killing the buyer.
- Target down-payment help for first-gen/first-time buyers so they start with lower LTV.
- Keep amortization front and center — because that’s the thing that quietly turns “I pay for housing” into “I own housing.”
That’s the spirit of the 1930s reforms. Stretching to 50 years is… not that.
Bottom Line
So yes — Trump did the visual judo of putting himself next to FDR and saying “30-year” vs. “50-year.” Smart politics. But when you run the math on today’s median price and today’s rate — and especially when you run it on the FHA buyer — what you actually get is a product that makes the payment look better while making the family pay the bank for an extra 20 years.
That’s not the American mortgage tradition FDR built. That’s just a longer bill.


RELATED ARTICLES
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score. Learn how zero-balance accounts, credit utilization, and installment loans affect your FICO score—and why financial progress matters more than maximizing every point.
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the right reasons doesn't guarantee financial success. Explore how interest, hidden fees, limited savings, and unequal homeownership opportunities can turn supposedly good debt into a lasting...
1 Comment
Leave Comment
Cancel reply
Gig Economy
American Middle Class / Oct 23, 2026
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score. Learn how zero-balance accounts, credit utilization, and installment loans affect your...
By Article Posted by Staff Contributor
American Middle Class / Oct 22, 2026
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the right reasons doesn't guarantee financial success. Explore how interest, hidden fees,...
By MacKenzy Pierre
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From Florida's homestead exemptions to Massachusetts zoning reform and California's affordable housing...
By Article Posted by Staff Contributor
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover how new rules from federal housing regulators could affect mortgage approvals,...
By Article Posted by Staff Contributor
American Middle Class / Oct 13, 2026
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what something actually costs. From buy now, pay later services to longer...
By Article Posted by Staff Contributor
American Middle Class / Oct 12, 2026
Fair Capitalism: We Don’t Need to Abolish Capitalism. We Need to Fix It.
Fair capitalism means preserving entrepreneurship and profits while ensuring working Americans share more meaningfully in the prosperity they help create.
By MacKenzy Pierre
American Middle Class / Oct 12, 2026
The Sunday Scaries: How Financial Independence Can Help You Reclaim Your Weekend
The Sunday Scaries can begin long before Monday morning. Building emergency savings, lowering monthly expenses, and increasing financial independence may help you reclaim your weekend.
By Article Posted by Staff Contributor
Business / Aug 08, 2026
The Missing Middle in Black Entrepreneurship
Black entrepreneurship has expanded dramatically. The next challenge is helping more Black-owned businesses move from self-employment to employer firms and sustainable scale.
By FMC Editorial Team
Personal Finance / Aug 01, 2026
Cash Strategy: Put Every Dollar in the Right Place
Your checking account, emergency fund, short-term savings, and investments should not be managed the same way. This cash strategy helps assign every dollar to the right...
By Article Posted by Staff Contributor
Personal Finance / Aug 01, 2026
Best HYSA: How to Choose Beyond the Highest APY
A competitive interest rate matters, but it is only one part of choosing a high-yield savings account. Compare insurance, fees, access, transfer speed, and promotional conditions.
By Article Posted by Staff Contributor
Latest Reviews
American Middle Class / Oct 23, 2026
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score....
American Middle Class / Oct 22, 2026
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the...
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From...
Pingback: Portable Mortgages for the Middle Class - FMC