
Health Insurance as Startup Infrastructure:
By FMC Editorial Team
The estimated reading time for this post is 541 seconds
Health Insurance as Startup Infrastructure: How the ACA Opened the Door to Entrepreneurship—and how the 2026 Subsidy Cliff Could Slam It Shut
Dek: The Affordable Care Act didn’t “create entrepreneurs.” It did something more practical: it lowered the penalty for leaving payroll work by making health coverage portable. The scheduled expiration of enhanced ACA subsidies after December 31, 2025 risks rebuilding the very lock the law helped loosen.
Executive summary
- Entrepreneurship lock is real. When health insurance is tied to a job, starting a business often means gambling with your family’s coverage.
- The ACA reduced that lock by protecting people with preexisting conditions, building Marketplaces, and subsidizing premiums so coverage could follow the person—not the employer.
- The best empirical work finds measurable increases in self-employment among people most constrained by pre-ACA individual-market barriers—exactly where you’d expect the effect to show up.
- But the affordability bridge is wobbling. Enhanced premium tax credits (the more generous subsidy rules) are scheduled to expire after Dec. 31, 2025, reverting on Jan. 1, 2026.
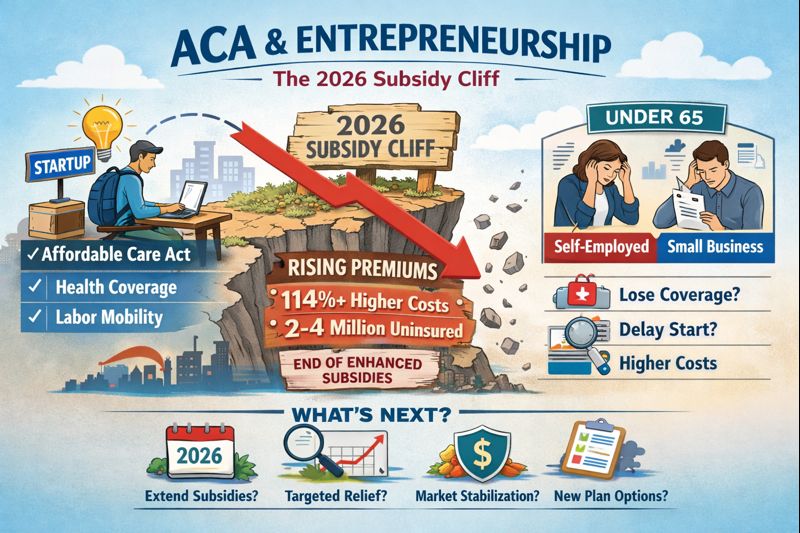
- Premium shock isn’t hypothetical. KFF estimates that, without an extension, subsidized Marketplace enrollees’ premium payments would rise 114% on average in 2026 (about $1,016 more per year), more than doubling what many households pay now.[
- Coverage loss is expected. CBO estimates 2.2 million more people would be uninsured in 2026 if the enhanced subsidies lapse; other modeling (Urban Institute) projects roughly 4.8 million becoming uninsured in 2026 under similar assumptions.[4][5]
- Congress hasn’t reached a deal heading into late December 2025; multiple reports describe any fix slipping into January 2026, which adds uncertainty on top of rising sticker prices.
- This is an economic policy choice, not just a health policy choice. When net premiums jump, people delay quitting jobs, postpone launching ventures, or go uninsured—each outcome dulls local economic dynamism.
- Most workable path: a multi-year extension (or durable reform) of enhanced credits paired with market-stabilizing tools (like reinsurance) and administrative simplification to reduce churn.
1) What the ACA changed: the mechanism behind “freedom to start”
In the U.S., entrepreneurship has never been just about ideas. It has always been about risk—especially the kind of risk that doesn’t show up in a pitch deck.
Health coverage is the clearest example. If your insurance comes through your employer, leaving that employer is not a clean transition. It’s a cliff. Before the ACA, the individual market could price people out, exclude conditions, or deny coverage outright. That reality kept plenty of would-be founders anchored to payroll jobs even when their skills, ambition, and market opportunity said “go.”
The ACA attacked that anchor through a set of blunt, practical interventions:
- Guaranteed access: ACA-compliant plans can’t refuse you because your medical history is complicated.
- A real purchase channel: Marketplaces made individual coverage legible—plans, prices, enrollment rules, and assistance in one place.[1]
- Subsidies that move with income: Premium tax credits lowered what many households pay out of pocket.
- A floor for low-income adults (where adopted): Medicaid expansion offered coverage that can survive volatile earnings—exactly the pattern early-stage founders often face.
Put those pieces together and you get something that looks less like “health reform” and more like economic infrastructure: a risk-management system that allows people to leave jobs without losing medical security.
2) What the research shows (and what it doesn’t)
Policy arguments about entrepreneurship are usually built on stories. Stories matter, but they aren’t evidence. The serious question is whether we can observe behavioral change after the ACA among people most likely to be locked in place by insurance risk.
One of the cleaner findings in the literature is that the ACA increased self-employment for groups with high demand for health insurance—people who, before the ACA, faced the steepest penalties for buying coverage outside an employer. In other words: the effect shows up where the theory says it should.
That’s important for two reasons:
- It suggests the ACA’s portability provisions did more than reshuffle coverage; they changed labor-market choices at the margin.
- It avoids the lazy claim that “the ACA caused a startup boom.” The evidence is more modest—and more credible.
Limits still matter. Self-employment is an imperfect proxy for entrepreneurship. Not every new LLC is a high-growth firm. And the strength of the ACA’s effect depends on local market conditions (insurer competition, premium levels) and state policy (Medicaid expansion). So the honest conclusion isn’t that the ACA turned everyone into a founder. It’s that it made the option of founding less punishing for the people previously trapped by medical risk.
3) The 2026 subsidy cliff: why “ballooning premiums” is not an exaggeration
The looming problem is not that the ACA disappears on January 1, 2026. The architecture remains. The problem is that the more generous subsidy rules—enhanced premium tax credits—are scheduled to end after December 31, 2025, reverting on January 1, 2026.
When the enhanced credits lapse, many households face a sharper version of the same reality: the sticker price of coverage is rising, and the cushion between sticker and what you actually pay gets thinner—or vanishes for some.
KFF’s estimate is blunt: without an extension, premium payments for subsidized Marketplace enrollees would rise 114% on average in 2026—about $1,016 more per year, on average.[3] “Average” hides the pain. Premium impacts vary by age, location, plan choice, and income. But as a policy signal, a doubling of what people pay is the kind of shock that changes behavior.
Coverage losses follow affordability losses. CBO estimates that 2.2 million additional people would be uninsured in 2026 if enhanced subsidies are not extended. The Urban Institute projects a larger hit—roughly 4.8 million becoming uninsured in 2026—depending on modeling assumptions.
Congress’s posture worsens the damage. Late-December reporting describes lawmakers heading into year-end without an agreement to extend the subsidies, pushing any possible fix into January 2026. Even if a deal eventually materializes, uncertainty is not neutral. People plan around worst-case scenarios when it comes to healthcare costs.
4) Why this hits entrepreneurs first: cash flow, risk, and timing
Founders don’t fear “costs.” They fear unpredictable fixed costs. Rent is predictable. Software subscriptions are predictable. Health premiums—when policy is uncertain—are not.
The typical early-stage entrepreneur lives in the gap between idea and steady income. Revenue can be uneven. Client contracts slide. One slow quarter becomes two. In that environment, a sudden jump in net premiums isn’t just annoying—it changes the launch calculus.
When net premiums spike, would-be founders tend to respond in a handful of predictable ways:
- Delay the leap. Keep the job, keep the coverage, postpone the venture.
- Downshift the idea. Choose a smaller, safer model that can be run alongside payroll work.
- Go uninsured. A risky bet that can turn a medical event into business failure.
- Rely on fragile stopgaps. Short-term coverage strategies that don’t match the reality of multi-year startup runways.
This is also a geography story. Premiums differ dramatically across states and counties, driven by insurer competition and underlying healthcare prices. KFF has shown that the burden of the subsidy expiration is uneven and, in some places, severe. If you want to understand why entrepreneurship clusters in certain regions, don’t ignore healthcare affordability. It quietly shapes who can afford to take a risk.
One more detail that matters: 2026 sticker prices are already moving. KFF estimates Marketplace insurers are raising premiums substantially for 2026, which means the post-subsidy world would force more households to feel more of that increase directly. When the base cost rises and the subsidy shrinks, the squeeze multiplies.
5) Policy menu: four paths, real tradeoffs
There’s no single “right” policy. There are options with costs and consequences. The key is to evaluate them the way entrepreneurs would: by asking what they do to volatility, not just averages.
Option A: Extend enhanced premium tax credits (multi-year or permanent)
What it does: Prevents the 2026 affordability shock and stabilizes expectations.
Upside: Preserves portability and labor mobility; reduces the odds that would-be founders stay stuck in jobs for coverage.
Downside: Budget impact is real; CBO has shown sizable deficit effects for packages that include subsidy extensions.
Option B: Target the cliff (limit extreme spikes rather than extending everything)
What it does: Focuses resources on households most exposed to losing subsidies or facing very high net premiums.
Upside: Lower fiscal cost than a full extension; reduces the most dramatic premium jumps.
Downside: Adds complexity and new “edges,” where a small income change triggers a big premium change—exactly the kind of instability founders can’t manage.
Option C: Pair a smaller subsidy extension with reinsurance and market stabilization
What it does: Lowers premiums by reducing insurer risk exposure and improving the risk pool.
Upside: Addresses sticker prices, not just what consumers pay; can help stabilize local markets.
Downside: Design matters; poorly targeted stabilization can move costs around without changing underlying drivers.
Option D: Alternative coverage approaches (e.g., association health plans) instead of extension
What it does: Tries to lower premiums for some groups by offering different plan structures.
Upside: Politically appealing to some lawmakers; may offer lower premiums for healthier groups.
Downside: Risk pool fragmentation can raise costs in ACA-compliant markets and weaken the very protections that reduce entrepreneurship lock.
6) Counterarguments (and the parts worth keeping)
“Most entrepreneurs can use a spouse’s plan.” Some can. Many can’t. And the research that finds the strongest ACA effects tends to focus on people without easy alternative sources of coverage—precisely because that’s where lock is binding.
“Subsidies just mask high healthcare costs.” True, subsidies don’t fix hospital pricing or pharmaceutical costs. But they do affect behavior, because behavior responds to net premiums. A sudden doubling of net premiums is a behavioral event, not an accounting detail.
“Extending subsidies is too expensive.” Cost matters. But so do the costs of coverage loss and labor-market rigidity. CBO’s uninsured estimates are not abstract; they imply more uncompensated care and more medical debt risk—both of which hit small business owners hard.
Conclusion: if Congress wants growth, stop treating Marketplace affordability like a footnote
The ACA’s underrated achievement is simple: it made it less dangerous to leave a job. That’s not a cultural shift. It’s a change in the downside math.
Letting enhanced subsidies expire after December 31, 2025 risks rebuilding entrepreneurship lock by making the cost of going independent jump sharply—at the exact moment many households are already staring at rising 2026 sticker premiums. KFF’s estimate of a 114% average premium-payment increase is the kind of shock that reshapes plans in real time.
A serious pro-entrepreneurship agenda would do three things: lock in a multi-year subsidy policy so households can plan, stabilize premiums where markets are thin, and reduce administrative churn so people don’t fall in and out of coverage because their income fluctuates month to month.
In startup terms, this isn’t complicated: you can’t build new businesses on top of a trapdoor.


RELATED ARTICLES
I Was Sour on AI Before the Jensen Huang Scandal
We're investing trillions in artificial intelligence while its biggest proponents promise nothing short of a transformed civilization. I'm not convinced. AI can help experienced professionals work faster and deepen their knowledge, but it cannot put in their 10,000 hours or...
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score. Learn how zero-balance accounts, credit utilization, and installment loans affect your FICO score—and why financial progress matters more than maximizing every point.
Leave Comment
Cancel reply
Gig Economy
Business / Nov 15, 2026
I Was Sour on AI Before the Jensen Huang Scandal
We're investing trillions in artificial intelligence while its biggest proponents promise nothing short of a transformed civilization. I'm not convinced. AI can help experienced professionals work...
By MacKenzy Pierre
American Middle Class / Oct 23, 2026
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score. Learn how zero-balance accounts, credit utilization, and installment loans affect your...
By Article Posted by Staff Contributor
American Middle Class / Oct 22, 2026
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the right reasons doesn't guarantee financial success. Explore how interest, hidden fees,...
By MacKenzy Pierre
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From Florida's homestead exemptions to Massachusetts zoning reform and California's affordable housing...
By Article Posted by Staff Contributor
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover how new rules from federal housing regulators could affect mortgage approvals,...
By Article Posted by Staff Contributor
American Middle Class / Oct 13, 2026
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what something actually costs. From buy now, pay later services to longer...
By Article Posted by Staff Contributor
American Middle Class / Oct 12, 2026
Fair Capitalism: We Don’t Need to Abolish Capitalism. We Need to Fix It.
Fair capitalism means preserving entrepreneurship and profits while ensuring working Americans share more meaningfully in the prosperity they help create.
By MacKenzy Pierre
American Middle Class / Oct 12, 2026
The Sunday Scaries: How Financial Independence Can Help You Reclaim Your Weekend
The Sunday Scaries can begin long before Monday morning. Building emergency savings, lowering monthly expenses, and increasing financial independence may help you reclaim your weekend.
By Article Posted by Staff Contributor
Business / Aug 08, 2026
The Missing Middle in Black Entrepreneurship
Black entrepreneurship has expanded dramatically. The next challenge is helping more Black-owned businesses move from self-employment to employer firms and sustainable scale.
By FMC Editorial Team
Personal Finance / Aug 01, 2026
Cash Strategy: Put Every Dollar in the Right Place
Your checking account, emergency fund, short-term savings, and investments should not be managed the same way. This cash strategy helps assign every dollar to the right...
By Article Posted by Staff Contributor
Latest Reviews
Business / Nov 15, 2026
I Was Sour on AI Before the Jensen Huang Scandal
We're investing trillions in artificial intelligence while its biggest proponents promise nothing short of a...
American Middle Class / Oct 23, 2026
Why Paying Off Debt Can Lower Your Credit Score—and Why That Isn’t Always Bad
Paying off a loan or closing a credit card can sometimes lower your credit score....
American Middle Class / Oct 22, 2026
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the...