
How to Fit Credit Card Payoff into the 50/30/20 Rule Without Starving Your Savings
By Article Posted by Staff Contributor
The estimated reading time for this post is 513 seconds
Let’s be honest: when most people say they’re “doing the 50/30/20 rule,” what they really mean is:
- 50% to needs
- 30% to wants
- 20% to vibes
Meanwhile the credit card balance sits in the corner, quietly compounding at 22-ish percent interest a year. The average rate on accounts being charged interest was about 22.8% in mid-2025.
Nationwide, credit card balances have pushed over $1.2 trillion, with the average cardholder carrying around $5,600–$6,600 in balances.
You can’t build serious wealth with that kind of drag on your back.
So how do you use the 50/30/20 rule when you’ve got real card debt—without killing your savings completely and setting yourself up for the next emergency swipe?
That’s what this “Part 2” is about.
Quick Refresher: What 50/30/20 Was Actually Designed to Do
The 50/30/20 rule—popularized by Elizabeth Warren in All Your Worth—was meant to be a simple, sustainable split of your after-tax income:
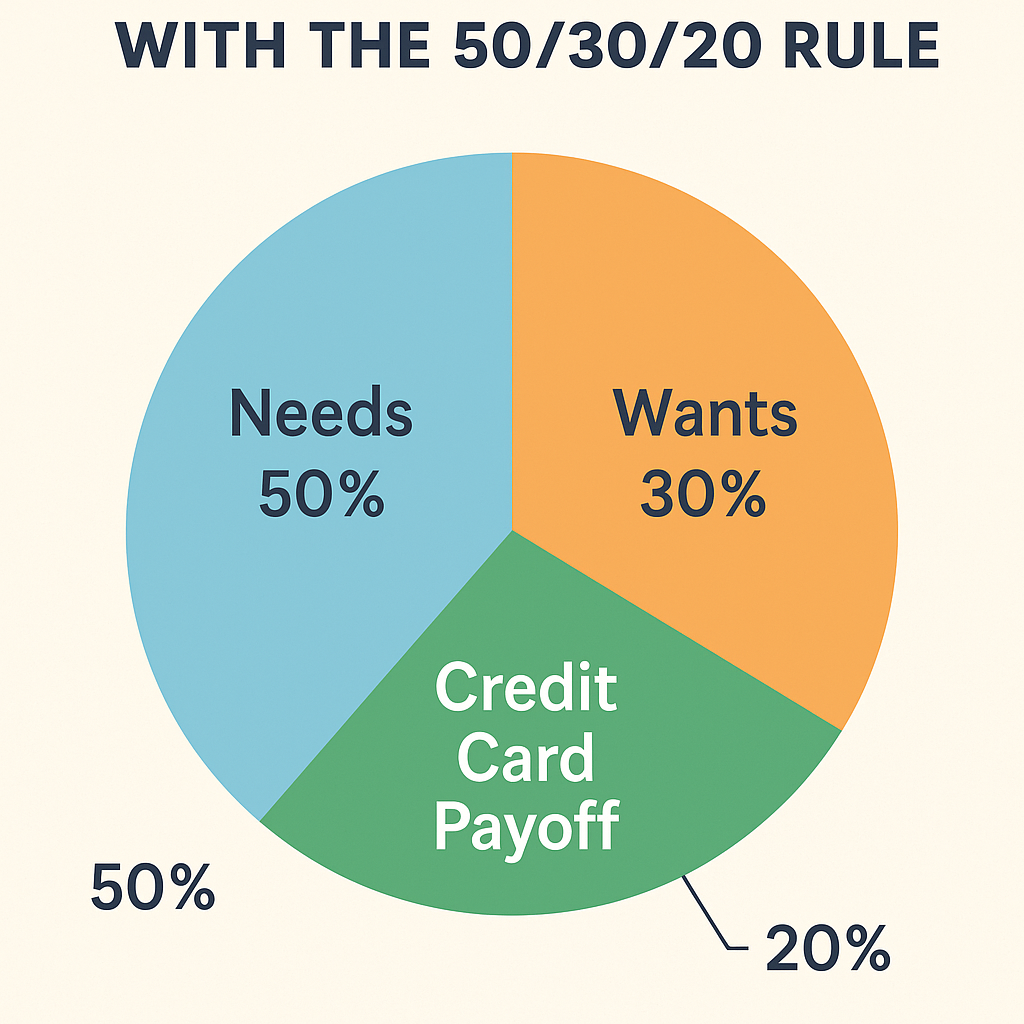
50% → Needs (housing, basic food, utilities, transportation, insurance, minimum debt payments)
30% → Wants (restaurants, travel, upgrades, “it would be nice”)
20% → Savings and extra debt payoff
That last line is where the magic lives. Savings and extra debt payoff are on the same team. The rule never said, “Ignore debt until you max out your 401(k).” It also never said, “Pay every spare dollar to debt while your savings sit at $0.”
It’s a tension on purpose. You have to balance today’s emergencies with tomorrow’s freedom.
Why Credit Card Debt Deserves Special Treatment
Not all debt is equal. A fixed-rate 4% mortgage is not your enemy. A 23% variable credit card you’ve been carrying for three years is.
Credit card debt hits you three ways:
- High interest. Average rates over 22% mean a $5,000 balance can easily cost you more than $1,000 a year in interest if you only make minimums.
- Psychological drag. It keeps you in “I’ll catch up someday” mode.
- Future theft. Every dollar going to interest is a dollar that can’t go to future you.
Even with some recent improvements—Bankrate reports that about 46% of cardholders carry a balance, down a bit from last year—credit card debt is still one of the biggest wealth leaks for the middle class.
So yes, we want to attack it aggressively. But not blindly.
Phase 0: Before You Even Talk About 50/30/20
If you’re:
- Behind on rent or utilities,
- Dodging collections calls, or
- Choosing between basic medicine and minimum payments,
you’re not in “50/30/20 land” yet. You’re in stabilize the patient mode.
In that case:
- Get current on essential bills first.
- Talk to creditors about hardship programs or payment plans.
- Look for quick, ethical ways to bump income in the short term.
Once the basics are current and the fires are out, then the 50/30/20 framework becomes useful.
Phase 1: Build a Starter Emergency Buffer (So You Don’t Swipe Again)
Remember that Bankrate stat? Around 59% of Americans can’t handle a $1,000 emergency from savings. When that’s you, every flat tire goes on the card—and your payoff plan dies before it starts.
So the first job of the 20% bucket is not getting fancy with snowball spreadsheets. It’s building a starter emergency buffer, fast.
For most households, that looks like:
- $1,000–$2,000 in a boring savings account or
- One month of bare-bones expenses if your life is unstable
During this phase, it’s okay if:
- Retirement contributions are small or just enough to get a match.
- Extra payments to credit cards are modest.
The goal is to break the “swipe-then-panic” cycle. Once you’ve got a small cushion, the card stops being your emergency fund.
Phase 2: Splitting the 20% Between Savings and Debt
With a starter buffer in place, you can start using the 20% for its full job: savings and extra debt payoff.
Here’s the key:
You don’t need the perfect split. You need a split you can actually sustain.
Let’s say your take-home pay is $5,000 a month.
- 20% of that is $1,000.
- That $1,000 is your “future-you” bucket.
There are three main ways to slice it.
Option A: Heavy-Debt Mode (0/20 split)
| Bucket | % of Take-Home | $ on $5,000 Income |
|---|---|---|
| Extra savings | 0% | $0 |
| Extra debt payoff | 20% | $1,000 |
Who this is for:
- You have high-interest card debt (20%+ APR).
- You have at least a $1,000–$2,000 emergency buffer already.
- You’re emotionally ready to sprint.
This is the intense season: you funnel the entire 20% to credit cards on top of minimums. You use the debt avalanche (highest interest rate first) if you want maximum math efficiency, or the debt snowball (smallest balance first) if you need quick psychological wins.
The trade-off: retirement savings might be limited to your employer match for a short period. That’s okay for a season if it gets you out of 23% interest prison.
Option B: Balanced Attack (5/15 split)
| Bucket | % of Take-Home | $ on $5,000 Income |
|---|---|---|
| Extra savings | 5% | $250 |
| Extra debt payoff | 15% | $750 |
Who this is for:
- You’ve got meaningful credit card debt, but not at crisis levels.
- You want to keep building savings and/or retirement without dragging out the debt forever.
Here, you might:
- Put 5% into retirement or long-term savings (401(k), Roth IRA, etc.).
- Throw 15% at extra card payments using avalanche or snowball.
This is often the sweet spot for middle-class households who want to hit debt hard and sleep at night knowing savings is still moving.
Option C: Safety-First Mode (10/10 split)
| Bucket | % of Take-Home | $ on $5,000 Income |
|---|---|---|
| Extra savings | 10% | $500 |
| Extra debt payoff | 10% | $500 |
Who this is for:
- Your income is unstable or your industry feels shaky.
- You’re a chronic worrier who sleeps better with more cash on hand.
- Your debt rate is painful but not “hair on fire.”
Here, you build up:
- A larger emergency fund (3–6 months),
- Retirement savings,
- Possibly sinking funds (so you don’t relive this debt cycle),
while still making meaningful extra payments.
Will the math say you’re not being “optimal”? Maybe. But wealth-building is about behavior you’ll stick to, not lab-perfect equations.
Where the 30% “Wants” Bucket Comes In
So far, we’ve talked only about the 20%. But the dirty little secret of most debt payoffs is this:
The money for aggressive debt payoff has to come from somewhere—usually the 30% wants bucket.
You don’t free up 15–20% of your take-home by clipping coupons alone. You free it up by:
- Shrinking restaurants, bars, and delivery.
- Slashing random Amazon and “quick run to Target” spending.
- Cutting subscriptions you forgot you had.
- Replacing “we deserve this” with “we deserve to be debt-free.”
For a while, your 30% wants might look more like 20%. That’s okay. 50/30/20 is a guideline, not a moral score.
In practice, your real split might be:
- 50% needs
- 20% wants
- 30% future-you (savings + debt payoff)
That’s not failure. That’s focus.
But What About Retirement—Aren’t I Already Behind?
Yes, Americans are generally behind on retirement savings. That’s real. But being so terrified of being “behind” that you refuse to tackle 23% interest debt is like worrying about the wallpaper color while the house is on fire.
A few principles to keep you grounded:
- Try hard not to turn off free money.
- If your employer matches 401(k) contributions, fight to at least get the match even while paying off debt. That’s an instant 50–100% return right there.
- If your employer matches 401(k) contributions, fight to at least get the match even while paying off debt. That’s an instant 50–100% return right there.
- Short, intense sprints are better than endless half-efforts.
- It can make sense to do a 12–18 month heavy-debt sprint where your retirement contributions are minimal, as long as you flip the switch and raise them once the cards are gone.
- It can make sense to do a 12–18 month heavy-debt sprint where your retirement contributions are minimal, as long as you flip the switch and raise them once the cards are gone.
- Debt payoff is a form of investing.
- Knocking out a 22% card balance is the same as earning a 22% guaranteed return—tax-free—on that money.
- Knocking out a 22% card balance is the same as earning a 22% guaranteed return—tax-free—on that money.
The mistake isn’t temporarily prioritizing debt payoff. The mistake is never switching gears once the balance hits zero.
How to Keep from Falling Back Into the Same Hole
You’ve seen this story: someone fights their way out of debt and, a few years later, they’re right back in it.
That’s usually because they never changed the structure of their money. They just white-knuckled their way through a payoff.
To avoid that, bake these into your post-debt life:
- Keep the 20% bucket intact.
- When the card is gone, you don’t “get your 20% back” for lifestyle upgrades. You redirect the entire 20% into savings and investing.
- When the card is gone, you don’t “get your 20% back” for lifestyle upgrades. You redirect the entire 20% into savings and investing.
- Maintain sinking funds.
- Car repairs, holidays, and other predictable expenses should be funded monthly so they never run through a credit card again.
- Car repairs, holidays, and other predictable expenses should be funded monthly so they never run through a credit card again.
- Lock in automatic transfers.
- Automate retirement contributions and savings transfers so they happen without willpower.
- Automate retirement contributions and savings transfers so they happen without willpower.
- Keep a written “debt-free plan.”
- Literally write down how you’ll use that freed-up payment once the card is dead—extra retirement, future home down payment, etc.
- Literally write down how you’ll use that freed-up payment once the card is dead—extra retirement, future home down payment, etc.
Your job isn’t just to get out of the hole. It’s to fill it in behind you.
Putting It All Together: A Realistic 50/30/20 With Debt
Here’s what a realistic month might look like for a household taking home $5,000 with meaningful credit card debt:
- Needs (50%): $2,500
- Rent, basic food, utilities, transportation, insurance, minimum payments.
- Rent, basic food, utilities, transportation, insurance, minimum payments.
- Wants (20–25%): $1,000–$1,250
- Restaurants, streaming, travel, upgrades—but trimmed on purpose.
- Restaurants, streaming, travel, upgrades—but trimmed on purpose.
- Future-You (25–30%): $1,250–$1,500
- 5–10% to savings & retirement
- 15–20% to extra credit card payoff
- 5–10% to savings & retirement
That might not match the “clean” 50/30/20 graphic on the internet. But it matches real life for someone serious about killing debt and building security.
The exact split you pick—0/20, 5/15, 10/10—matters less than one thing:
Every month, a predictable slice of your income is walking out the door to build your future and destroy your high-interest debt.
No more “whatever’s left over.” No more “I’ll pay extra when I can.” You’re putting credit card payoff inside the 50/30/20 rule, not treating it as a side quest.
The Goal: Turn the 20% Into Fuel, Not a Fire Extinguisher
You don’t escape credit card debt by finding the perfect budgeting formula on Instagram. You escape it by:
- Putting your needs on a leash,
- Being honest about your wants, and
- Turning that 20% bucket into a consistent engine for savings and debt payoff.
For a while, debt will take the lion’s share. That’s okay. Just make sure:
- You build a small emergency cushion first.
- You don’t forget retirement exists.
- You have a plan for that 20% after the debt is gone.
Then 50/30/20 stops being a cute graphic and starts being what it was meant to be: a simple structure that moves you out of “I’ll catch up someday” and into “My money finally has a job—and high-interest debt isn’t the boss anymore.”


RELATED ARTICLES
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the right reasons doesn't guarantee financial success. Explore how interest, hidden fees, limited savings, and unequal homeownership opportunities can turn supposedly good debt into a lasting...
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From Florida's homestead exemptions to Massachusetts zoning reform and California's affordable housing initiatives, explore the potential effects on homeowners, renters, first-time buyers, and middle-class finances.
Leave Comment
Cancel reply
Gig Economy
American Middle Class / Oct 22, 2026
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the right reasons doesn't guarantee financial success. Explore how interest, hidden fees,...
By MacKenzy Pierre
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From Florida's homestead exemptions to Massachusetts zoning reform and California's affordable housing...
By Article Posted by Staff Contributor
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover how new rules from federal housing regulators could affect mortgage approvals,...
By Article Posted by Staff Contributor
American Middle Class / Oct 13, 2026
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what something actually costs. From buy now, pay later services to longer...
By Article Posted by Staff Contributor
American Middle Class / Oct 12, 2026
Fair Capitalism: We Don’t Need to Abolish Capitalism. We Need to Fix It.
Fair capitalism means preserving entrepreneurship and profits while ensuring working Americans share more meaningfully in the prosperity they help create.
By MacKenzy Pierre
American Middle Class / Oct 12, 2026
The Sunday Scaries: How Financial Independence Can Help You Reclaim Your Weekend
The Sunday Scaries can begin long before Monday morning. Building emergency savings, lowering monthly expenses, and increasing financial independence may help you reclaim your weekend.
By Article Posted by Staff Contributor
Business / Aug 08, 2026
The Missing Middle in Black Entrepreneurship
Black entrepreneurship has expanded dramatically. The next challenge is helping more Black-owned businesses move from self-employment to employer firms and sustainable scale.
By FMC Editorial Team
Personal Finance / Aug 01, 2026
Cash Strategy: Put Every Dollar in the Right Place
Your checking account, emergency fund, short-term savings, and investments should not be managed the same way. This cash strategy helps assign every dollar to the right...
By Article Posted by Staff Contributor
Personal Finance / Aug 01, 2026
Best HYSA: How to Choose Beyond the Highest APY
A competitive interest rate matters, but it is only one part of choosing a high-yield savings account. Compare insurance, fees, access, transfer speed, and promotional conditions.
By Article Posted by Staff Contributor
Personal Finance / Aug 01, 2026
High-Yield Savings vs. CDs, Treasury Bills, and Other Safe Places for Cash
High-yield savings accounts are excellent for accessible cash, but they are not always the best choice. Compare HYSAs, CDs, Treasury bills, money market accounts, and I...
By Article Posted by Staff Contributor
Latest Reviews
American Middle Class / Oct 22, 2026
The Problem With “Good Debt”
Mortgages, student loans, and business financing are often called good debt. But borrowing for the...
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From...
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover...