
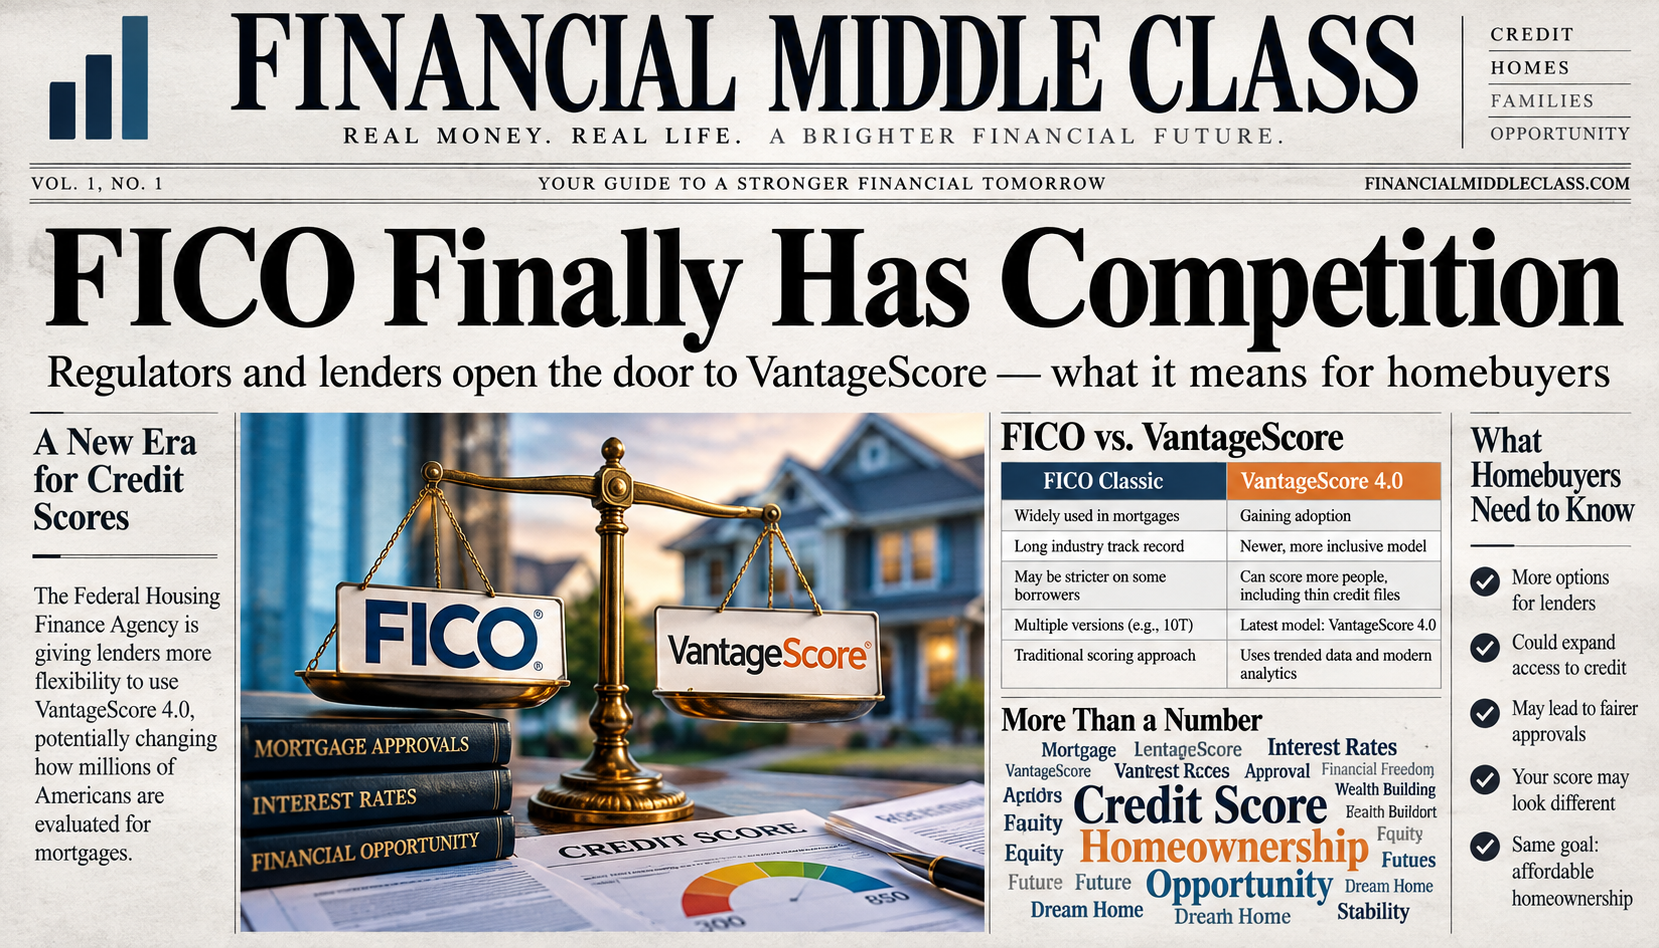
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
By Article Posted by Staff Contributor
The estimated reading time for this post is 1482 seconds
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now lenders can use a competing model backed by the three major credit bureaus. The shift could lower borrowing costs and expand access to homeownership, but it also raises questions about how lenders measure risk—and who ultimately benefits.
Financial Middle Class | October 14, 2026
The American mortgage industry is undergoing a significant change in how it evaluates borrowers, one that could affect who qualifies for a home loan and how much they pay for it.
For decades, lenders selling mortgages to Fannie Mae and Freddie Mac relied on established FICO credit-scoring models. Those scores became a common language for measuring borrowers’ credit risk across a mortgage market involving trillions of dollars in outstanding loans.
That long-standing arrangement is beginning to give way to competition.
Under changes directed by the Federal Housing Finance Agency (FHFA), lenders can now use either Classic FICO or VantageScore 4.0, a competing scoring model developed by a company jointly owned by Equifax, Experian, and TransUnion, for eligible mortgages sold to Fannie Mae and Freddie Mac.
The transition is gaining momentum.
In September, 37% of conventional mortgage applications created in Fannie Mae’s Desktop Underwriter system included a VantageScore 4.0 credit score, according to the company. The figure measures applications, not completed mortgages, but it demonstrates how rapidly lenders have begun testing an alternative to the industry’s established standard.
Rocket Mortgage, one of the country’s largest mortgage lenders, announced in late September that it would make VantageScore 4.0 its preferred scoring model for eligible loans during the fourth quarter.
The company said testing showed that the newer model helped some borrowers qualify for mortgages and reduced closing costs for others.
Federal regulators argue that introducing competition will modernize credit scoring, encourage innovation, and potentially improve access to homeownership.
But the change has also created concerns among mortgage analysts and investors.
VantageScore 4.0 often produces higher scores than Classic FICO when evaluating the same borrower. That can improve a consumer’s mortgage pricing without changing the underlying financial circumstances of the person taking out the loan.
For an individual borrower, that difference could be welcome.
For institutions guaranteeing or investing in mortgages, it raises a more complicated question: Does the higher score reflect a better assessment of creditworthiness, or simply a different measurement of the same risk?
The distinction matters because credit scores influence not only individual mortgage decisions but also how lenders, guarantors, and investors price risk throughout the housing-finance system.
For consumers, the development presents an opportunity as well as a reason for caution. More competition may lead to better mortgage terms, but a higher score does not automatically mean a lower borrowing cost—or a more affordable home.
How FICO Became the Mortgage Industry’s Standard
To understand the significance of the new competition, it helps to understand how FICO became so deeply embedded in American lending.
Fair Isaac Corporation was founded in 1956 by engineer Bill Fair and mathematician Earl Isaac. The company helped pioneer statistical methods that allowed lenders to evaluate creditworthiness using measurable characteristics of borrowers’ financial histories.
Credit scoring brought an important innovation to consumer lending.
Instead of relying primarily on an individual loan officer’s assessment of a borrower’s financial reliability, lenders could use statistical models to estimate the probability of future repayment problems.
The approach offered greater consistency, made it easier to process large volumes of applications, and helped financial institutions manage credit risk across entire loan portfolios.
FICO’s scoring models eventually became widely used by banks, credit-card issuers, auto lenders, and mortgage companies.
Their influence in the mortgage market grew alongside the development of automated underwriting and the expansion of mortgage securitization.
Fannie Mae and Freddie Mac were central to that development.
The two government-sponsored enterprises generally do not make home loans directly to consumers. Instead, they purchase qualifying mortgages from lenders, providing those institutions with funds that can support additional lending.
Many of the acquired mortgages are packaged into mortgage-backed securities, which are sold to investors. Fannie Mae and Freddie Mac guarantee payments on securities they issue.
For this system to function efficiently, lenders, guarantors, and investors need consistent information about the loans being originated and sold.
Credit scoring provides part of that information.
As Fannie Mae and Freddie Mac incorporated FICO models into their mortgage standards, the company’s scores became an important component of the secondary mortgage market.
Lenders seeking to sell qualifying mortgages to the enterprises generally needed to obtain the designated versions of FICO scores.
The result was a powerful competitive advantage.
Other credit-scoring systems existed, but they faced substantial barriers to gaining acceptance in a market whose infrastructure had been built around FICO.
Lenders had little incentive to replace a scoring model that investors, mortgage insurers, regulators, and technology providers already understood.
FICO’s position was therefore more than a reflection of brand recognition or consumer preference. It was reinforced by the operating requirements of institutions that help finance a substantial portion of American homeownership.
That standardization delivered benefits. It also made the mortgage industry difficult for competing scoring companies to enter.
The Federal Housing Finance Agency began evaluating changes to the enterprises’ credit-scoring requirements in 2014. Congress accelerated the effort through legislation enacted in 2018, establishing a formal process to evaluate alternative models.
The resulting transformation would take years.
VantageScore Challenges an Established Business Model
VantageScore entered the credit-scoring market in 2006, when Equifax, Experian, and TransUnion jointly established the company.
Its ownership structure makes the competition unusual.
The three credit bureaus maintain information about consumers’ borrowing and repayment histories. FICO develops scoring models that use information from those credit files.
VantageScore also develops credit-scoring models, but its owners are the same three companies that maintain the underlying credit data.
That arrangement creates a competitive relationship between the independent scoring company and the major credit-reporting companies on which the broader credit-scoring business relies.
It also raises questions about how scoring products are priced, licensed, and distributed.
For most consumers, these commercial relationships are largely invisible.
Someone applying for a mortgage may understand that their credit report comes from Equifax, Experian, or TransUnion. They may know their FICO score or see a VantageScore through a financial application.
What they are less likely to know is which companies receive fees when a lender orders those scores, how much the scoring models cost, or how those costs are passed through the mortgage process.
The introduction of VantageScore into the conventional mortgage market increases the pressure on all of these companies to compete.
In October 2025, FICO announced a direct mortgage-score licensing program designed to allow certain credit-report resellers to obtain and distribute FICO scores without using the traditional credit-bureau distribution arrangement.
Under one pricing option, the company established a $4.95 charge per score and an additional $33 fee per borrower per score when a mortgage is funded. A separate option offered a $10-per-score charge without that funded-loan fee structure.
FICO said the program was designed to reduce certain scoring costs and provide lenders with more pricing flexibility.
Those charges are part of commercial licensing arrangements. They should not be confused with a borrower’s total credit-report fee or mortgage closing costs.
Still, the change is revealing.
FICO is not simply defending its established position by arguing that its scoring models are more accurate. It is also changing how its products are distributed and priced.
That is one of the clearest indications that the emergence of a competitor is altering the business of mortgage credit scoring.
Federal Regulators Change the Rules
The turning point came in October 2022, when FHFA approved two newer credit-scoring models for use by Fannie Mae and Freddie Mac: VantageScore 4.0 and FICO 10T.
Both models were designed to incorporate information that older scoring systems did not use in the same way, including changes in consumer credit behavior over time.
The original regulatory plan contemplated a transition to both newer models, accompanied by changes in the credit-reporting process.
That proved more complicated than initially anticipated.
Mortgage lenders, credit-reporting agencies, loan-origination technology providers, mortgage insurers, and securities investors needed time to adapt their systems and risk models.
After industry feedback and implementation delays, FHFA adopted an interim approach in July 2025 permitting lenders to choose between Classic FICO and VantageScore 4.0.
The change began taking effect in April 2026 through a limited rollout.
On September 9, FHFA expanded the option to all approved Fannie Mae and Freddie Mac lenders, eliminating the requirement for prior written approval.
Lenders may now choose either model for an eligible loan, provided they comply with the enterprises’ requirements. A lender must use the same scoring model for every borrower on a given mortgage, though it can select a different approved model for another loan.
A further development followed on September 30, when Fannie Mae and Freddie Mac aligned their upfront mortgage-pricing adjustments across Classic FICO and VantageScore 4.0.
That adjustment established a common pricing framework for eligible loans delivered using either model.
FICO 10T remains approved by FHFA but has not yet been implemented for Fannie Mae and Freddie Mac loan delivery. The agency has said Classic FICO is expected to be retired eventually, although no date has been announced.
For now, the market is operating under a transitional system in which lenders have greater flexibility to select the score used for an eligible mortgage.
That flexibility is a significant change from the former arrangement.
It also means that the scoring model selected by a lender may become an increasingly important factor in mortgage pricing.
FICO vs. VantageScore: Why the Same Borrower Can Receive Different Scores
The new competition is not simply a contest between an older company and a newer one.
Both companies have developed multiple credit-scoring models, and the versions involved can produce different results from the same underlying credit information.
Classic FICO refers to the established versions traditionally used in conventional mortgage lending.
VantageScore 4.0 incorporates newer analytical methods, including trended credit information that allows the model to examine aspects of a consumer’s financial behavior over time.
FICO 10T also incorporates trended data and represents FICO’s more modern approach to predicting credit risk.
| Feature | Classic FICO | VantageScore 4.0 | FICO 10T |
|---|---|---|---|
| Developer | Fair Isaac Corporation | VantageScore Solutions | Fair Isaac Corporation |
| Score range | 300–850 | 300–850 | 300–850 |
| General approach | Established models using traditional credit-report information | Modern scoring using credit trends and broader available data | Modern FICO scoring using credit trends |
| Trended credit data | Not incorporated in the same way | Yes | Yes |
| Reported rent payments | More limited treatment | Can be considered when available | Can be considered when available |
| Current Fannie/Freddie delivery status | Eligible | Eligible for qualifying loan types | Approved but not yet available for delivery |
One advantage of newer scoring models is their ability to distinguish between borrowers whose current balances look similar but whose recent financial behavior differs.
Consider two consumers who each owe $3,000 on a credit card with a $10,000 limit.
Both have a current credit-utilization ratio of 30%.
But their recent histories could be very different.
One consumer may have reduced an $8,000 balance to $3,000 over the preceding year, demonstrating a sustained effort to reduce debt.
The other may have increased a balance from $500 to $3,000 over the same period.
A scoring model that evaluates trends in balances and payments may be able to distinguish between those patterns.
That does not mean the consumer reducing debt will necessarily receive a higher score. Other credit-history factors still matter, and the models’ precise calculations are proprietary.
It does, however, illustrate the potential value of additional information.
Newer models can provide a more detailed view of certain aspects of credit behavior than an older approach focused more heavily on the current state of a credit file.
The more important question is whether that additional information produces a better prediction of repayment risk.
That is where independent research becomes particularly useful.
A Study of 27.5 Million Mortgages Reveals Important Differences
In September 2026, researchers at the Urban Institute published a comparison of Classic FICO, VantageScore 4.0, and FICO 10T.
The analysis, conducted by Laurie Goodman, Jun Zhu, and Todd Hill, examined approximately 27.5 million historical Fannie Mae mortgage loans for which all three scores were available.
The researchers compared the distribution of scores and the models’ ability to distinguish borrowers who subsequently experienced serious mortgage delinquency.
The results underscore why a higher credit score is not necessarily evidence of lower credit risk.
Both newer models assigned scores averaging approximately 13 points above Classic FICO in the historical sample.
They also placed a substantially larger proportion of mortgages in the highest score category.
About 31% of loans received a score of at least 800 under VantageScore 4.0 or FICO 10T. Under Classic FICO, approximately 14% scored that high.
| Historical loan comparison | Classic FICO | VantageScore 4.0 | FICO 10T |
|---|---|---|---|
| Share of loans scoring 800 or higher | 14% | 31% | 31% |
| Average score relative to Classic FICO | Baseline | About 13 points higher | About 13 points higher |
| Default-risk ranking | Performed well | Outperformed Classic FICO on the study’s highlighted measure | Strongest on that measure |
Source: Urban Institute, September 11, 2026. Figures refer to the historical mortgage sample, not the entire U.S. adult population.
The difference in the share of mortgages receiving scores above 800 is particularly striking.
A borrower who appears to be in an exceptionally strong credit category under one model may fall into a different category under another.
But the underlying borrower has not changed.
The models have assigned different numerical interpretations to the same credit history.
That distinction is critical for the mortgage industry because investors and lenders have spent years associating certain FICO score ranges with observed repayment outcomes.
A score of 780 under VantageScore 4.0 cannot automatically be assumed to represent the same probability of default as a 780 under Classic FICO.
The Urban Institute study found that all three models were effective at ranking borrowers according to credit risk.
FICO 10T identified the largest share of defaults in the highest-risk portion of the sample, followed by VantageScore 4.0 and Classic FICO.
The researchers also examined alternative definitions of default and different economic conditions, finding that their relative rankings remained consistent.
Those results suggest that the newer models offer meaningful analytical improvements over Classic FICO. They do not establish that every consumer is evaluated more accurately by one particular model.
Nor do they demonstrate that every borrower receiving a higher score should automatically qualify for cheaper credit.
There is another limitation.
The research studied mortgages that had already been originated. It therefore could not directly determine how many people previously denied a mortgage would have qualified under the newer models, or how those additional borrowers would perform.
That matters because expanding access to credit is one of the central arguments being advanced in favor of VantageScore.
The number of additional people who can receive a score is not the same as the number who can safely afford a mortgage.
The Financial-Inclusion Argument
One of VantageScore’s strongest selling points is its ability to evaluate consumers who have limited conventional credit histories.
Under traditional credit-scoring practices, consumers have generally needed a sufficient history of reported credit activity to receive a score.
That can disadvantage people who manage their finances primarily through debit cards, cash, or deposit accounts rather than traditional borrowing products.
It may also affect renters whose housing payments are not reflected in their credit reports.
A consumer who has paid rent consistently for years has demonstrated the ability to meet a recurring financial obligation. Yet those payments have not always contributed to conventional credit scores.
VantageScore 4.0 can consider reported rental-payment data when the information is available.
FICO 10T can also incorporate certain reported rent-payment information.
Neither model automatically receives every rent payment made in America. The relevant information must be available in the credit-reporting system, and its effect depends on the model and the borrower’s circumstances.
VantageScore has promoted research estimating that approximately 33 million more adults can receive scores under VantageScore 4.0 than under Classic FICO or FICO 10T.
The company has also highlighted research suggesting that nearly five million additional consumers could be considered mortgage-ready under certain scoring assumptions.
Those figures illustrate the potential size of the market for newer scoring approaches. But they are estimates advanced through VantageScore-supported research, not verified counts of new homeowners.
They also depend on assumptions about what qualifies a consumer as mortgage-ready.
A score above a particular threshold cannot independently establish whether someone has sufficient income, savings, or financial stability to support a mortgage.
The financial-inclusion argument is nevertheless substantial.
When a scoring model overlooks reliable evidence of payment behavior, qualified consumers may have fewer borrowing opportunities than their financial histories justify.
More comprehensive data could improve that assessment.
But the objective should be to identify borrowers more accurately, not simply to increase the number of people receiving favorable scores.
Better financial inclusion and responsible underwriting need to advance together.
Will the Competition Lower Mortgage Costs?
For prospective homebuyers, the most immediate question is whether VantageScore can make a mortgage less expensive.
There is evidence that it can benefit some borrowers.
On September 28, Rocket Mortgage announced that it had evaluated approximately 1.4 million credit reports using FICO and VantageScore models during 2026.
The company said its testing showed that VantageScore 4.0 helped some applicants meet credit requirements and move forward in the mortgage process.
For borrowers who realized financial savings by using VantageScore 4.0, Rocket reported an average reduction of $1,600 in closing costs.
That is a meaningful amount for households already facing substantial expenses when purchasing a home.
But the qualification is important: the $1,600 figure is an average among borrowers who saved money, not an average across every applicant or mortgage originated by Rocket.
The company did not establish that all borrowers would obtain similar benefits, and its findings were company-reported rather than independently verified industrywide results.
Still, the announcement suggests that lenders see potential financial advantages in using a competing scoring model.
One reason involves loan-level price adjustments.
Fannie Mae and Freddie Mac use pricing frameworks that account for certain mortgage characteristics, including credit scores and loan-to-value ratios.
These adjustments affect the upfront economics of mortgages sold to the enterprises and may be reflected in the interest rates or other charges lenders offer borrowers.
A borrower whose score improves enough to move into a more favorable pricing category may therefore obtain a less expensive mortgage.
Consider a hypothetical $400,000 mortgage.
If using an eligible alternative scoring model resulted in an otherwise identical offer with an upfront pricing charge 0.25 percentage points lower, the difference would amount to $1,000.
| Illustrative comparison | Mortgage A | Mortgage B |
|---|---|---|
| Loan amount | $400,000 | $400,000 |
| Hypothetical upfront pricing charge | 1.00% | 0.75% |
| Dollar cost | $4,000 | $3,000 |
| Borrower savings | — | $1,000 |
Illustration only. The percentages are assumptions, not actual October 2026 lender quotes or specific Fannie Mae pricing-grid entries.
The benefit could be greater if a different scoring outcome also helped a borrower obtain a lower interest rate.
But these possibilities should not be confused with guaranteed savings.
Mortgage rates reflect a range of factors, including broader financial-market conditions, loan characteristics, lender pricing decisions, and borrower qualifications.
A higher credit score may improve the terms available to a consumer, but it does not guarantee the best mortgage offer.
There is also a difference between savings achieved by lenders and savings passed along to borrowers.
Competing scoring companies may reduce their licensing fees. Lenders could benefit from lower credit-reporting costs. But consumers will benefit only if lenders pass along those savings or if the resulting underwriting and pricing decisions produce better loan terms.
The distinction becomes especially important when considering how lender competition interacts with the mortgage securities market.
The Risk of Shopping for the Most Favorable Score
The new framework gives lenders flexibility to choose between Classic FICO and VantageScore 4.0 for eligible mortgages.
That could produce a benefit for a borrower whose VantageScore is substantially higher than their Classic FICO score.
It could also create incentives for lenders to favor the model that produces the most advantageous result.
The practice is sometimes described as credit-score shopping.
The concern is not that borrowers are doing anything improper or that the newer score must be inaccurate.
Rather, the issue is whether lenders selecting favorable scores could make mortgage portfolios appear less risky without a corresponding reduction in their underlying probability of default.
Suppose a borrower receives a Classic FICO score of 725 and a VantageScore 4.0 score of 755.
If both models are used within a common pricing framework, the higher score may lead to more favorable loan terms, depending on the mortgage’s other characteristics.
But the borrower’s income, debt, cash reserves, and repayment history remain the same.
For a lender trying to originate a competitive mortgage, the higher score may present an opportunity.
For an investor evaluating mortgage-backed securities, the question becomes how that score compares with the historical evidence used to estimate default risk.
If scores from different models have different relationships with default probability, treating the same numerical score as equivalent across models can distort risk assessments.
In July 2026, Urban Institute researchers examined how choosing more favorable credit scores could affect mortgage pricing and perceptions of credit risk.
Their analysis suggested that selecting higher reported scores could generate savings for some borrowers while also making it harder to compare the underlying risk of mortgage portfolios without appropriate adjustments.
That does not mean competition will necessarily lead to more defaults.
The study relied on historical data and modeled assumptions. It was not evidence that the new policy had already produced widespread deterioration in mortgage performance.
The concern is that poorly calibrated pricing could eventually create costs elsewhere in the financial system.
Fannie Mae and Freddie Mac guarantee large amounts of mortgage credit risk. Investors purchasing their securities also depend on reliable information about borrower characteristics.
If the relationship between reported scores and actual risk becomes less transparent, investors may require additional compensation for uncertainty.
Over time, that could place upward pressure on financing costs.
The outcome will depend partly on how successfully the industry recalibrates scoring and pricing models.
Recognizing the need for additional transparency, Fannie Mae and Freddie Mac have been expanding historical credit-score datasets and developing disclosures that provide investors with more information about the different models.
These measures are important because a competitive credit-scoring market does not necessarily have to sacrifice consistent risk assessment.
It does, however, require the industry to understand what each score actually measures.
FICO’s Next Competitor May Be Its Own Newer Model
The current contest between Classic FICO and VantageScore 4.0 may not represent the mortgage industry’s ultimate scoring arrangement.
FICO 10T has already received regulatory approval and is expected to become available for Fannie Mae and Freddie Mac loan deliveries in a future phase of implementation.
The model incorporates trended credit information and offers many of the modern analytical features that distinguish VantageScore 4.0 from Classic FICO.
FICO has emphasized research finding that 10T performs better than VantageScore 4.0 in predicting mortgage defaults.
In May 2026, FICO publicized an analysis by actuarial firm Milliman, involving nearly 20 million mortgages, that found FICO 10T delivered stronger risk differentiation across several mortgage categories.
Those results deserve consideration. They also need to be evaluated in the context of other research, including the populations examined, the performance measures used, and the study’s commercial sponsorship.
The September Urban Institute study likewise found that FICO 10T performed particularly well at identifying borrowers in the highest-risk segment of its sample.
That complicates a narrative in which VantageScore represents technological innovation and FICO represents only an aging standard.
The more meaningful distinction may ultimately be between older and newer scoring methodologies, rather than between the two companies.
Once FICO 10T becomes available for eligible Fannie Mae and Freddie Mac mortgages, lenders could face a different competitive landscape.
The questions will be whether the newer models improve prediction, expand access to responsible credit, offer sustainable pricing, and justify the operational costs of adopting them.
That would be a more substantive competitive test than simply comparing which company produces the higher average credit score.
For Borrowers, More Choice Does Not Mean More Control
Despite the shift toward competition, borrowers generally do not control which credit-scoring model a mortgage lender uses.
That decision remains subject to the lender’s policies and the mortgage product’s requirements.
Consumers can ask lenders whether VantageScore 4.0 is available for the financing they are seeking. They can compare offers from lenders using different approved scoring models.
But they should not assume that a higher VantageScore will produce a better mortgage or that the score displayed in a banking application is the same version used for mortgage underwriting.
The distinction between scoring and underwriting is particularly important.
In November 2025, Fannie Mae eliminated the minimum third-party credit-score requirement for mortgage applications evaluated through its Desktop Underwriter system.
The change removed the former 620-point minimum screening requirement within that system.
Desktop Underwriter uses Fannie Mae’s proprietary risk-assessment framework, which examines broader credit information and mortgage characteristics.
Fannie Mae’s internal assessment also incorporates credit trends and certain rental-payment information.
Third-party credit scores remain relevant to applicable loan-pricing and delivery requirements, and manually underwritten mortgages can have different rules.
Therefore, removing a minimum score from an automated underwriting system does not guarantee mortgage approval.
A borrower still needs to satisfy income, debt, asset, documentation, property, and other applicable requirements.
For households planning to purchase a home, the practical implications are straightforward.
A prospective borrower should know which credit-scoring model a lender uses, review the underlying credit reports for errors, and compare actual mortgage terms rather than relying solely on a numerical score.
The Consumer Financial Protection Bureau recommends requesting Loan Estimates from multiple lenders.
Those standardized disclosures allow borrowers to compare interest rates, annual percentage rates, closing costs, mortgage insurance, and other important terms.
That advice becomes more important—not less—as lenders gain flexibility in how they evaluate creditworthiness.
The benefit of receiving a higher score means little if another lender offers a less expensive mortgage overall.
The Real Test Is Whether Competition Produces Better Lending
The introduction of VantageScore into the conventional mortgage market is a significant change in an industry that has relied on familiar credit-scoring standards for decades.
It could generate several benefits.
Competition may encourage scoring companies to reduce licensing costs, develop better models, and recognize financially responsible behavior that older systems fail to capture adequately.
Lenders may gain flexibility to evaluate borrowers using additional information. Some borrowers may obtain better pricing or qualify for financing that previously would have been unavailable.
At the same time, regulators and investors have legitimate reasons to insist that greater flexibility not weaken risk assessment.
The consequences of inadequate mortgage underwriting are not confined to individual lenders.
They can affect investors, financial institutions, government guarantors, and ultimately the wider economy.
That makes credit-score competition different from competition in many ordinary consumer markets.
The companies developing the scores are selling analytical products to lenders. Consumers generally do not select those products directly, even though the results can influence some of their most consequential financial decisions.
A competitive market is therefore not necessarily one in which consumers automatically receive the greatest benefit.
The evidence needed to judge this transition will take time to develop.
Policymakers and researchers will need to examine whether the newer scores produce more sustainable mortgage approvals, whether borrowers actually receive lower costs, and whether the resulting loans perform as well as expected.
They will also need to determine whether additional scoring coverage translates into meaningful improvements in access for borrowers with limited traditional credit histories.
For American households, there is a broader lesson.
A credit score is an important financial tool, but it is not a complete measure of a person’s financial condition.
Someone with a strong score may still lack the income or savings needed to afford a house. Another person may have sufficient resources and a reliable payment history but receive a less favorable score because the available credit data do not fully capture that record.
Better scoring models may reduce some of these shortcomings.
They cannot eliminate the underlying challenges of housing affordability.
The introduction of VantageScore will not produce more homes, increase household incomes, or erase the financial burden of property taxes, insurance, and mortgage interest.
Those remain substantial barriers to homeownership for many middle-class households.
What competition can potentially accomplish is narrower but still important: making sure that people who are financially prepared to borrow are evaluated using accurate, relevant information and offered terms that appropriately reflect their risk.
For FICO and VantageScore, success will be measured partly through market share, licensing revenue, and lender adoption.
For mortgage lenders, it will be measured through loan performance, costs, and profitability.
For investors, it will depend on whether the scores provide reliable information about the loans they finance.
But for borrowers, the most meaningful measure will be simpler.
Does a more competitive credit-scoring system help qualified households obtain mortgages on better terms without exposing them—or the broader housing market—to risks that have merely been overlooked?
The competition has started.
Whether it produces a better mortgage market remains to be seen.
Sources and Research Notes
Federal regulation and mortgage policy
Federal Housing Finance Agency — Credit Scores. Official regulatory timeline, September 2026 lender expansion, and October 2026 pricing changes.
Fannie Mae — Credit Score Models and Reports Initiative. Approved models, loan eligibility requirements, and September 2026 adoption data.
Fannie Mae — Simplified Pricing Across Credit Score Models. September 30, 2026.
Fannie Mae — Desktop Underwriter Credit Risk Assessment Updates. Changes to the automated underwriting process.
Independent mortgage research
Urban Institute — Assessing Credit Risk with Classic FICO, FICO 10T, and VantageScore 4.0. Laurie Goodman, Jun Zhu, and Todd Hill, September 11, 2026.
Urban Institute — How Credit Score Shopping Might Affect Federal Mortgage Lending and the Perceived Risk of Default. Laurie Goodman and Jun Zhu, July 24, 2026.
Industry developments and disclosures
Rocket Mortgage — VantageScore Adoption Announcement. September 28, 2026.
FICO — Mortgage Direct Licensing Program. October 2025.
FICO — Mortgage Predictive Performance Research. May 4, 2026.
VantageScore — Mortgage Scoring Research. July 10, 2026.
Consumer guidance
Consumer Financial Protection Bureau — Request and Compare Loan Estimates.


RELATED ARTICLES
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what something actually costs. From buy now, pay later services to longer auto loans and installment financing, businesses are making expensive purchases appear more manageable by...
Fair Capitalism: We Don’t Need to Abolish Capitalism. We Need to Fix It.
Fair capitalism means preserving entrepreneurship and profits while ensuring working Americans share more meaningfully in the prosperity they help create.
Leave Comment
Cancel reply
Gig Economy
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover how new rules from federal housing regulators could affect mortgage approvals,...
By Article Posted by Staff Contributor
American Middle Class / Oct 13, 2026
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what something actually costs. From buy now, pay later services to longer...
By Article Posted by Staff Contributor
American Middle Class / Oct 12, 2026
Fair Capitalism: We Don’t Need to Abolish Capitalism. We Need to Fix It.
Fair capitalism means preserving entrepreneurship and profits while ensuring working Americans share more meaningfully in the prosperity they help create.
By MacKenzy Pierre
American Middle Class / Oct 12, 2026
The Sunday Scaries: How Financial Independence Can Help You Reclaim Your Weekend
The Sunday Scaries can begin long before Monday morning. Building emergency savings, lowering monthly expenses, and increasing financial independence may help you reclaim your weekend.
By Article Posted by Staff Contributor
Business / Aug 08, 2026
The Missing Middle in Black Entrepreneurship
Black entrepreneurship has expanded dramatically. The next challenge is helping more Black-owned businesses move from self-employment to employer firms and sustainable scale.
By FMC Editorial Team
Personal Finance / Aug 01, 2026
Cash Strategy: Put Every Dollar in the Right Place
Your checking account, emergency fund, short-term savings, and investments should not be managed the same way. This cash strategy helps assign every dollar to the right...
By Article Posted by Staff Contributor
Personal Finance / Aug 01, 2026
Best HYSA: How to Choose Beyond the Highest APY
A competitive interest rate matters, but it is only one part of choosing a high-yield savings account. Compare insurance, fees, access, transfer speed, and promotional conditions.
By Article Posted by Staff Contributor
Personal Finance / Aug 01, 2026
High-Yield Savings vs. CDs, Treasury Bills, and Other Safe Places for Cash
High-yield savings accounts are excellent for accessible cash, but they are not always the best choice. Compare HYSAs, CDs, Treasury bills, money market accounts, and I...
By Article Posted by Staff Contributor
American Middle Class / Aug 01, 2026
High-Yield Savings Accounts: A Safer Home for Your Cash
A high-yield savings account can pay several times the national savings rate while keeping qualified deposits federally insured. Here is how it works, what to watch...
By Article Posted by Staff Contributor
Real Estate / Jul 30, 2026
Mortgage Lock-In Is Freezing the Housing Market
Millions are trapped by 3% mortgages. Learn how mortgage lock-in worsens affordability—and why homeowners are renovating instead.
By FMC Editorial Team
Latest Reviews
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover...
American Middle Class / Oct 13, 2026
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what...
American Middle Class / Oct 12, 2026
Fair Capitalism: We Don’t Need to Abolish Capitalism. We Need to Fix It.
Fair capitalism means preserving entrepreneurship and profits while ensuring working Americans share more meaningfully in...