A Realistic Approach to Budgeting
Imagine sitting down with your paycheck, trying to figure out how to stretch it across bills, groceries, rent, and maybe something fun like a concert. It’s easy to feel overwhelmed—like you’re playing a never-ending game of financial Tetris. That’s where the 50/30/20 Rule comes in.
This simple budgeting method divides your spending into three key categories: needs, wants, and savings. It’s like giving your paycheck a plan, so you can cover the essentials, treat yourself, and still prepare for the future. Let’s break down how it works—and more importantly—how you can make it work for you.
What is the 50/30/20 Rule?
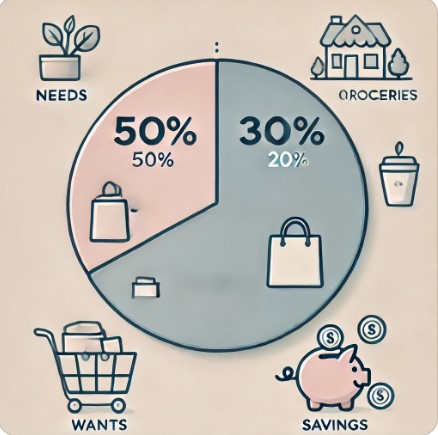
The 50/30/20 rule is a guideline that suggests splitting your after-tax income in the following way:
- 50% for needs: These are your essentials—things you literally can’t live without.
- 30% for wants: Think of this as the fun stuff, the expenses that make life enjoyable but aren’t strictly necessary.
- 20% for savings and debt repayment: This is your future fund—whether that means paying down debt or setting aside money for your long-term goals.
In theory, it sounds simple. But how does this rule actually fit into your life?
Why the 50/30/20 Rule Works
The beauty of the 50/30/20 rule lies in its simplicity. You don’t need to track every single purchase or categorize every cup of coffee. Instead, it provides a broad framework for managing your money with a balance between the present and future.
This method ensures you cover the essentials (your needs), enjoy life now (your wants), and build a cushion for the future (your savings). By following the 50/30/20 rule, you’re setting yourself up for both short-term satisfaction and long-term security—without spending hours creating a detailed budget.
Breaking It Down: Needs, Wants, and Savings
50%: Needs—The Non-Negotiables
We all have expenses that are simply non-negotiable. These are the things you must pay for to keep your life running. In this category, you’ll find the basics—everything from your rent to the groceries that stock your fridge.
Needs typically include:
- Rent or mortgage payments
- Utilities (electricity, water, gas)
- Groceries (not gourmet meals—just the essentials)
- Transportation (public transit, car payments, gas)
- Health insurance and medical expenses
Example: Let’s say you bring home $3,000 a month after taxes. According to the 50/30/20 rule, $1,500 (or 50%) should go toward your needs. If your rent is $1,200, that leaves you $300 to cover groceries, utilities, and transportation. If that feels tight, you might need to re-examine your needs or adjust your spending in other areas.
30%: Wants—The Fun Stuff
Next up is the fun part: your wants. This is where you get to enjoy the fruits of your labor, whether it’s a dinner out with friends, a new gadget, or a weekend getaway. But be careful—this is the category that can easily get out of hand if you’re not mindful.
Wants include things like:
- Dining out or ordering takeout
- Entertainment (concerts, movies, streaming services)
- Hobbies (gym memberships, shopping, recreational activities)
- Travel or vacation plans
Example: With that same $3,000 paycheck, $900 (30%) can go toward your wants. Maybe you decide to spend $100 on a night out, $50 on a new outfit, and $20 on a movie. That still leaves you with a chunk to enjoy other experiences, while sticking to your budget.
20%: Savings and Debt Repayment—Your Future Security
Finally, the last 20% goes toward what many of us tend to put off—savings and debt repayment. This is the category where you start building a financial safety net, and it’s one of the most important steps you can take toward long-term security.
Here’s what you should prioritize in this category:
- Building an emergency fund (aim for 3-6 months of living expenses)
- Contributing to retirement accounts (401(k), IRA, etc.)
- Paying down high-interest debt (credit cards, student loans)
- Saving for big goals (like a home, new car, or vacation)
Example: If you’re taking home $3,000, $600 (20%) should be directed toward savings or debt repayment. You could split it between building an emergency fund and paying down credit card debt, ensuring you’re making progress on both fronts.
How to Implement the 50/30/20 Rule
Ready to put the 50/30/20 rule into action? Here’s how to get started:
- Calculate your take-home pay: This is your income after taxes and deductions like health insurance. If your income fluctuates, use an average over the last few months.
- Categorize your spending: Look at your spending habits from the past month. Break it down into needs, wants, and savings/debt repayment categories. This will give you a clearer idea of where your money is going and where adjustments need to be made.
- Make adjustments: If your needs take up more than 50%, you might need to look for ways to reduce fixed costs. Can you cut your grocery bill or switch to a cheaper phone plan? If your wants are eating into your savings, maybe it’s time to scale back on the dining out.
- Automate savings: One of the easiest ways to stay consistent with the 50/30/20 rule is to automate your savings. Set up automatic transfers to your savings account so you don’t even have to think about it.
- Review and adjust regularly: Your financial situation changes over time, and so should your budget. Check in every few months to see if you need to tweak anything.
Common Pitfalls to Avoid
- Confusing wants with needs: Be strict with yourself—dining out, no matter how delicious, is a want, not a need.
- Neglecting savings: It’s tempting to skip saving in favor of fun experiences now, but your future self will thank you if you prioritize saving early.
Conclusion: Empower Your Financial Future
The 50/30/20 rule gives you a practical, easy-to-follow framework to manage your money. It’s not about being overly restrictive but about finding balance. By setting aside 50% for your needs, 30% for your wants, and 20% for savings, you’re creating a budget that supports both your present lifestyle and future financial security.
So, take a moment to review your finances today. What changes can you make to align your budget with the 50/30/20 rule? It’s not about perfection—it’s about progress. Small steps now can make a huge difference later.