
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
By Article Posted by Staff Contributor
The estimated reading time for this post is 2033 seconds
Property taxes, zoning, affordable housing, and the cost of living: What voters need to understand before November 3.
Financial Middle Class | October 15, 2026
There is something increasingly peculiar about the American housing market.
A family can own a home for twenty years, watch its value double, and still feel less financially secure than it did a decade earlier.
On paper, that family may be wealthier. In practice, it could be dealing with a larger property-tax bill, increasingly expensive homeowners insurance, higher utility charges, and maintenance costs that consume a growing share of household income.
Meanwhile, a younger family earning what once would have been considered a comfortable middle-class salary may struggle to purchase a home in the very neighborhood where its parents bought one.
The older homeowners have an asset that is expensive to keep. The younger family has an income that is no longer enough to acquire that same asset.
Both families are confronting different versions of the same affordability problem.
And neither is particularly interested in being told that the economy is doing well if the evidence in their checking account suggests otherwise.
That tension helps explain why voters will encounter an unusually consequential collection of housing and tax proposals on November 3.
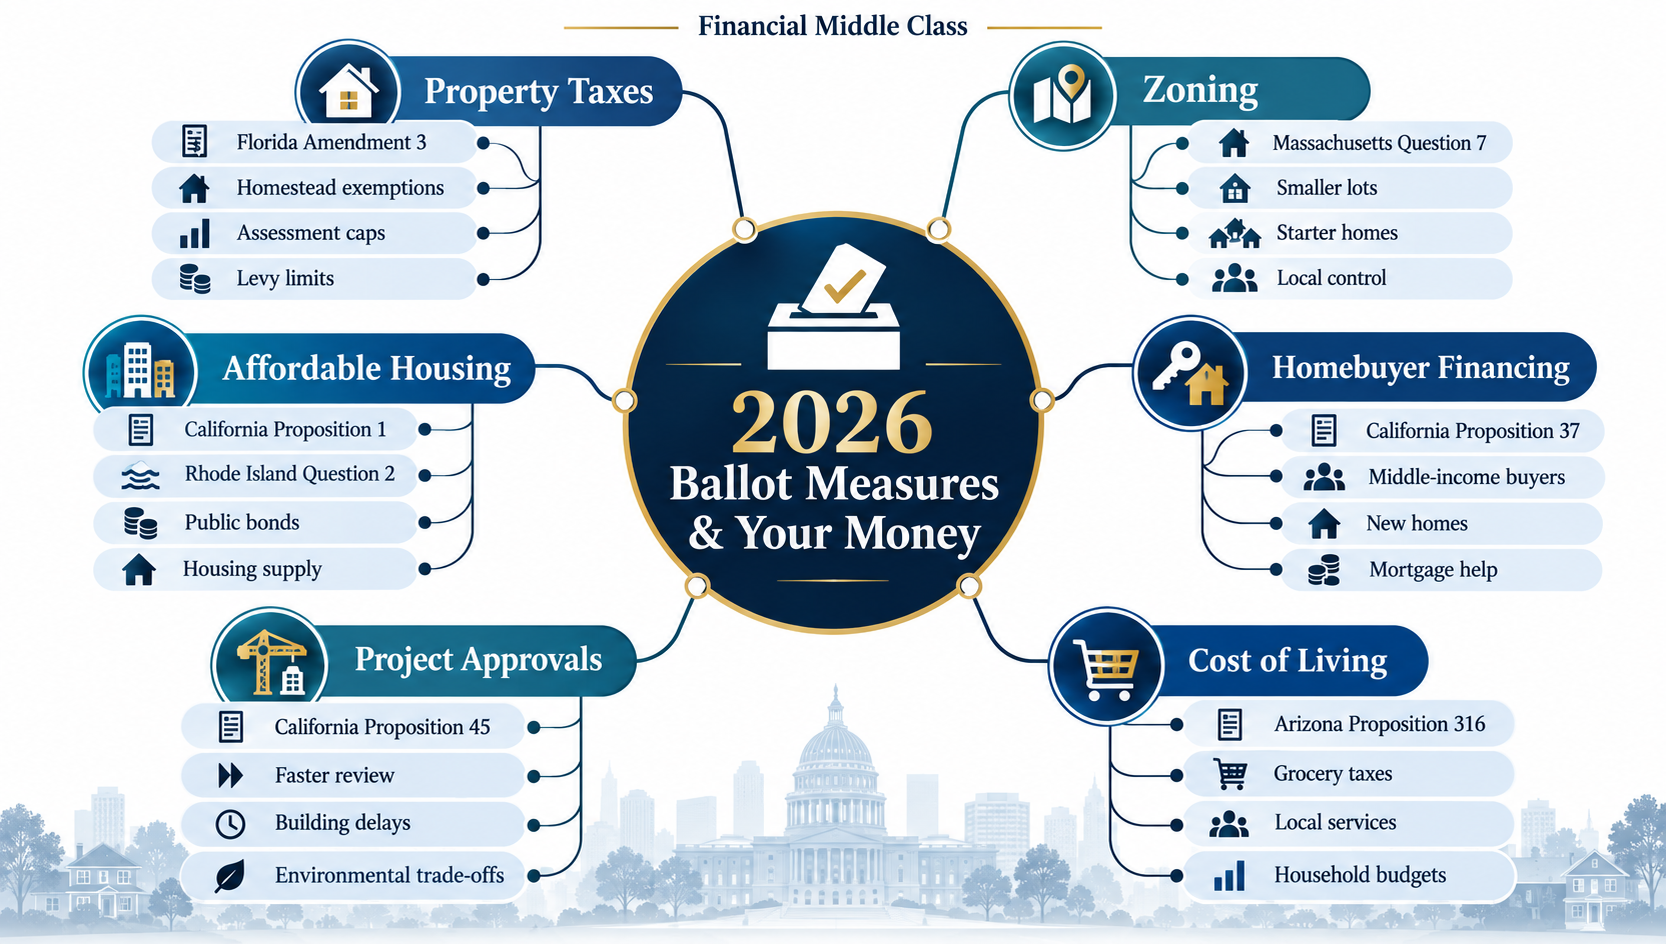
In Florida, voters will decide whether to substantially expand property-tax exemptions for qualifying homeowners. In Massachusetts, a statewide proposal would make it easier to construct single-family homes on smaller lots. In California, voters will consider billions of dollars in housing financing, mortgage assistance, and changes to environmental review procedures. Rhode Island will consider borrowing to finance additional housing.
Other states are debating how quickly property taxes should increase, how much of a home’s value should be taxable, and which government services should receive public funding.
These are different proposals, created in different political environments. Yet they point toward a common economic question.
How do Americans make housing more affordable without creating a different financial problem somewhere else?
That is not a question with a simple partisan answer. Nor is it something that can be resolved by one tax exemption, one housing program, or one change to zoning law.
It requires looking at how homes are financed, how communities grow, how governments raise revenue, and how the benefits and costs are distributed among the people who live there.
For middle-class Americans, those details matter far more than the campaign language surrounding them.
An Unusual Election for Housing and Tax Policy
Midterm elections typically focus on control of Congress, the president’s agenda, and the national economy.
Those questions remain important in 2026. But the ballots themselves tell another story.
According to the National Conference of State Legislatures, voters in 16 states will consider 30 tax-related proposals this November. Fifteen involve property taxes and 11 address income taxes.
That is a significant amount of tax policy being placed directly before voters. It also reveals where some of the economic pressure is being felt.
Property taxes have become a particularly visible concern in communities where home values increased sharply. Housing construction rules are drawing attention where development has failed to keep up with demand. Public financing proposals are appearing in states where building affordable housing has become increasingly difficult without government assistance.
These subjects overlap, but they should not be confused.
Lowering property taxes can reduce the cost of remaining in a home. It does not necessarily make the home cheaper to purchase.
Changing zoning regulations can increase the amount of land available for housing. It does not guarantee that developers will build on that land.
Mortgage assistance can help some families purchase homes. But if the program increases demand without increasing supply, part of the financial benefit may be absorbed into higher prices.
Government housing bonds can support construction. They also create financing obligations that must be repaid.
Understanding these distinctions is essential to interpreting the 2026 ballot.
Selected 2026 ballot measures affecting household finances
| State | Measure | What the proposal would do | Central economic question |
|---|---|---|---|
| Florida | Amendment 3 | Expand homestead property-tax exemptions | How much would eligible owners save, and what happens to local revenue? |
| Massachusetts | Question 7 | Allow qualifying single-family homes on smaller lots | Would increased development flexibility produce more attainable homes? |
| California | Proposition 1 | Authorize $11.25 billion in housing bonds | How much housing would public financing create or preserve? |
| California | Proposition 37 | Establish financing for eligible middle-income buyers | Would financing assistance improve access without raising prices? |
| California | Proposition 45 | Change environmental review procedures for certain projects | How should construction speed be balanced with environmental review? |
| Rhode Island | Question 2 | Authorize $120 million in housing bonds | Would the housing benefits justify the borrowing costs? |
| North Carolina | Property-tax amendment | Require state legislation limiting local levy increases | How should tax predictability be balanced with local budgets? |
| Oklahoma | State Question 847 | Reduce certain property assessment-growth limits | Who benefits from slower assessment growth? |
| Wyoming | Initiative 1 | Expand the exemption for qualifying primary residences | How would the tax benefits and revenue reductions be distributed? |
| Arizona | Proposition 316 | Restrict certain local grocery tax increases | How much would consumers save, and what revenue would cities lose? |
Sources: State election authorities, official legislative materials, and NCSL’s September 2026 ballot-measure reporting.
Florida’s Property-Tax Question: When Rising Home Values Become a Financial Burden
Start with Florida, where the argument over property taxes captures one of the strangest features of modern homeownership.
Imagine a couple who bought a modest home in 2010. They have made their mortgage payments, maintained the property, and watched the surrounding neighborhood become considerably more expensive.
Their home is now worth much more than they paid for it.
That sounds like financial success.
But if they want to remain in that home, appreciation alone does not pay the electric bill. It does not cover a homeowners insurance renewal or replace an aging roof.
And unless they sell, borrow against their equity, or generate income from the property, the increase in market value may do little to improve their cash flow.
Florida’s existing homestead and Save Our Homes rules already provide important limits and exemptions for qualifying homeowners. Those protections, however, do not eliminate every increase in carrying costs.
Amendment 3 would go further.
The proposal would increase the homestead exemption for non-school property taxes to $150,000 in 2027 and $250,000 in 2028, followed by inflation adjustments.
School property taxes would remain outside the expanded exemption.
For eligible homeowners whose assessed property values are sufficiently high, the change could reduce their annual tax bills.
That potential benefit is easy to understand. The complication is how the lost revenue would affect local government finances.
What a larger homestead exemption actually means
Property taxes generally depend on a property’s taxable assessed value and the rates imposed by the relevant taxing authorities.
An exemption reduces the portion of assessed value subject to specified taxes. It does not necessarily reduce the property’s market value, the mortgage balance, or every component of the total tax bill.
Consider a simplified example involving a home with an assessed value of $300,000 and a hypothetical non-school tax rate of 10 mills, or $10 per $1,000 of taxable value.
Assume, strictly for illustration, that $50,000 of the value is initially exempt from those taxes and that the homeowner qualifies for the proposed expanded exemption.
| Illustrative scenario | Taxable value | Non-school property tax |
|---|---|---|
| Current exemption assumption: $50,000 | $250,000 | $2,500 |
| Proposed 2027 exemption: $150,000 | $150,000 | $1,500 |
| Proposed 2028 exemption: $250,000 | $50,000 | $500 |
Under those assumptions, the annual non-school property-tax difference between the first and third examples would be $2,000.
That is meaningful money for many households.
It could help cover insurance premiums, home repairs, prescription costs, or retirement savings.
But this is an illustration, not an estimate for a particular Florida property. Actual exemptions, assessment limitations, tax districts, special assessments and millage rates can produce different results.
The equally important question is what happens to the local government revenue that would no longer be collected.
The homeowners’ benefit and the public-finance trade-off
Property taxes help support local services, including government operations, infrastructure, public safety and other functions.
If property-tax revenue falls, local governments may need to adjust spending, change fees or other revenues, or find alternative sources of financing.
Supporters of Amendment 3 emphasize the potential relief for homeowners, particularly retirees and longtime residents facing higher carrying costs.
Critics emphasize the possible loss of funding for public services and the prospect of shifting costs elsewhere.
Both arguments involve real financial considerations.
A homeowner might save money through a larger exemption while also experiencing changes in fees or government services. Whether that occurs, and to what extent, depends on the fiscal decisions made after implementation.
Renters occupy a different position.
They generally cannot claim homestead exemptions on properties they rent. They may nevertheless be affected by changes in local services, landlord operating costs, public fees, and the broader housing market.
That difference is worth emphasizing.
A measure that reduces the cost of owning an existing home is not necessarily a measure that makes it easier to become a homeowner.
Nor does every dollar in homeowner tax savings translate into an equivalent reduction in rents.
Florida’s proposed amendment is therefore about more than the size of a tax bill. It is about how the costs of local government should be distributed among property owners and other residents.
Property-Tax Relief Is Not One Policy: What North Carolina, Oklahoma, Wyoming and Tennessee Would Change
Florida’s approach is only one method for reducing or limiting property taxes.
Elsewhere, voters will consider measures that operate at entirely different points in the tax calculation.
North Carolina’s proposed constitutional amendment would require the General Assembly to establish limits on increases in the amount of property taxes local governments can levy.
Unlike an individual exemption, this concerns the growth of the overall property-tax levy. The ballot measure would not itself specify a numerical cap. Legislators would have to establish the details.
Oklahoma’s State Question 847 concerns limits on annual increases in the property values used for taxation.
Wyoming’s Initiative 1 would exempt half the value of qualifying primary residences from property taxes.
Tennessee’s Amendment 2 would prohibit state-level property taxation through its constitution, although Tennessee currently imposes no state property tax. That measure is primarily about future taxing authority rather than immediate savings on existing state property taxes.
These distinctions can be difficult to recognize because all four proposals are commonly discussed under the umbrella of property-tax relief.
But their effects would not be identical.
Four different tax mechanisms
| Proposal | What changes | What does not automatically change |
|---|---|---|
| North Carolina | Limits would be required on growth in local property-tax levies | The bill for every individual property is not necessarily frozen |
| Oklahoma | Certain increases in assessed property values would be more tightly limited | Tax rates and other charges could still change |
| Wyoming | A larger portion of qualifying home value would be exempt | Local revenue needs would not disappear |
| Tennessee | Future state-level property taxes would be constitutionally restricted | Existing local property taxes would remain |
Why does this matter?
Because governments can change tax bills through more than one channel.
A homeowner may have a relatively stable assessment but still face a higher tax bill if applicable rates change. Conversely, a community may reduce its tax rate even as property values increase.
Assessment caps may also create differences between established property owners and more recent buyers, depending on how values are reset when a property changes ownership.
That can affect mobility.
Someone who has owned a home for decades may benefit from a comparatively low taxable assessment. Moving to another home could mean losing part of that advantage, even when the new property is smaller.
Over time, such rules can influence whether people decide to sell, downsize, relocate for work, or remain where they are.
These are economic consequences that often receive less attention than the initial promise of tax relief.
And the debate leads naturally to another question: if keeping an existing home has become expensive, why has buying a new one become so difficult?
Massachusetts: The Housing Shortage Begins Before Anyone Pours the Foundation
There is a part of the housing affordability debate that rarely appears on a mortgage statement.
It is the amount of land that a local government requires underneath a home.
The price of land is one of the costs incorporated into the final purchase price of a house. Local zoning regulations help determine how many homes can be built on a parcel, what types of homes are allowed, and which development approvals are required.
Massachusetts Question 7 goes directly to that issue.
Under the measure, a single-family home could be constructed on a lot of at least 5,000 square feet in a residentially zoned area, provided the property has at least 50 feet of frontage and access to public water and sewer systems.
Communities would retain authority to reasonably regulate matters such as building height, setbacks, open space, parking, and short-term rental use.
The proposal is not a blanket authorization to construct any type of housing on any parcel.
Its focus is narrower: easing certain restrictions on the minimum amount of land required for a single-family home.
Why the size of a lot changes the economics
Consider a hypothetical acre of residential land.
An acre contains 43,560 square feet.
If zoning requires lots of 20,000 square feet, the theoretical number of homes permitted on that land is far smaller than if qualifying lots can be 5,000 square feet.
That does not mean an acre could automatically accommodate eight finished homes under the proposal. Streets, utilities, setbacks, parcel configuration and other requirements limit what can actually be constructed.
Still, the principle is straightforward.
When less land is required per home, the land cost allocated to each home may decline.
That can make smaller houses more financially feasible to build.
It may also offer a different kind of housing product: a detached home that does not require purchasing a large lot.
For first-time buyers, the distinction can be important.
A household may want a modest house close to work, family, transportation and schools. Existing zoning may limit the availability of that kind of property in the communities where it wants to live.
If developers must purchase expensive land and build on large lots, they may have an incentive to construct bigger, more expensive homes to recover their costs.
Smaller permitted lots can alter that calculation.
But zoning reform does not eliminate labor costs, materials expenses, financing charges, utility requirements or developer profit expectations.
It may change what can be built without guaranteeing what a finished home will sell for.
A dispute about affordability and local control
Supporters argue that Question 7 would make it easier to construct starter homes and allow young families and older residents to find more attainable housing.
Opponents argue that statewide rules could override local planning judgments involving infrastructure capacity, neighborhood design, environmental conditions and public services.
The argument is not simply between people who want housing and people who do not.
There are competing questions about how housing growth should occur, where sufficient infrastructure exists, and which level of government should establish the rules.
Massachusetts provides a useful national case study because zoning is frequently treated as a local concern even when its consequences extend far beyond municipal boundaries.
A town can restrict housing within its borders while the resulting shortage affects workers, employers and families throughout the surrounding region.
When that pattern occurs across numerous municipalities, the regional housing supply can become constrained.
Question 7 asks voters to decide how much statewide authority should intervene in those local decisions.
For readers interested in the economics rather than the politics, the central issue is whether changes in permitted housing supply would materially improve access, and what implementation costs or constraints might accompany those changes.
California: Three Housing Proposals That Attack Three Different Problems
California’s ballot offers one of the clearest demonstrations of how complicated housing affordability has become.
Three of its proposals approach the issue from different directions.
One would borrow money to finance affordable housing.
Another would establish financing assistance for qualifying middle-income homebuyers.
A third would revise procedures that can delay certain construction and infrastructure projects.
Although each relates to housing, they should not be treated as interchangeable solutions.
Proposition 1: Building and preserving affordable housing
Proposition 1 would authorize $11.25 billion in state general-obligation bonds for housing programs.
The funding would support activities including multifamily rental housing, preservation of existing affordable properties, housing for veterans, supportive housing, down-payment assistance and infrastructure.
According to California’s official voter information guide, repayment would increase state costs by an estimated $500 million to $600 million annually for approximately 25 years.
Those figures illustrate an important distinction in public finance.
Authorizing an $11.25 billion bond does not mean that the state will spend only $11.25 billion over the life of the obligation. Interest creates additional costs.
The economic argument for borrowing is that housing investments can be made before the government has accumulated sufficient cash to pay for them outright.
The trade-off is that future budgets carry debt-service commitments.
Whether that is financially worthwhile depends on the projects funded, their actual cost, the housing they produce or preserve, and the social and economic benefits generated over time.
For example, a publicly financed affordable apartment development might provide housing below prevailing market rents for eligible households.
But the affordability benefit must be evaluated alongside construction costs, ongoing operating requirements, the period for which units remain affordable, and the terms of the public financing.
A large bond authorization is a financial resource. It is not, by itself, a measurement of housing success.
Proposition 37: Helping qualified middle-income families finance a home
Proposition 37 approaches housing affordability through the buyer.
The measure would authorize up to $25 billion in bonds to finance fixed-rate mortgages covering as much as 17% of the purchase price of qualifying newly constructed homes or eligible converted properties.
Among the stated requirements, applicants would generally need to have lived in California for at least one year, earn less than 200% of the relevant area median income, occupy the purchased property and contribute a minimum 3% down payment.
The proposal specifies that borrowers’ mortgage payments, rather than direct state repayments, would service the bonds.
It is important not to describe the program simply as free down-payment money.
It is a financing mechanism with eligibility requirements and repayment obligations.
For middle-income buyers who can afford ongoing homeownership expenses but face challenges assembling the necessary cash or financing package, the program could improve access.
Still, financing availability and housing affordability are not quite the same thing.
Consider a hypothetical home priced at $500,000.
A financing program covering 17% of the purchase price would represent $85,000 in financing. That could significantly change how the purchase is structured for an eligible buyer.
It would not automatically reduce the $500,000 selling price.
And it would not remove ongoing costs such as insurance, taxes, maintenance and association fees.
That is why buyers should examine the entire financing arrangement rather than focusing only on the assistance amount.
Proposition 45: The cost of waiting to build
Proposition 45 addresses a different problem: how long certain projects spend in environmental review and related legal proceedings.
The measure would modify portions of California’s environmental review framework, including rules associated with the California Environmental Quality Act, or CEQA.
Supporters contend that review delays and litigation can raise development costs and prevent needed homes and infrastructure from being completed.
Opponents contend that limiting aspects of environmental review can weaken protections for communities exposed to pollution, development impacts and other environmental risks.
Both arguments involve costs, although some are easier to measure than others.
When a project takes longer to receive approval, financing expenses can accumulate. Labor and materials prices may change. Developers may hold land longer before producing any housing.
Those delays can increase the financial requirements of construction.
At the same time, environmental damage and inadequate infrastructure can impose costs on residents that are not fully reflected in a developer’s original construction budget.
Environmental review is partly intended to identify and address those risks.
The policy challenge is determining which procedures are necessary, which are unnecessarily burdensome, and what standards should govern any changes.
Three proposals, three economic mechanisms
| California proposal | Primary problem addressed | How the policy operates | Important limitation |
|---|---|---|---|
| Proposition 1 | Financing for affordable housing supply | Government bond financing for housing programs | Projects require time, execution and debt repayment |
| Proposition 37 | Access to home-purchase financing | Mortgage financing for eligible buyers | Assistance does not guarantee lower home prices |
| Proposition 45 | Development review costs and delays | Changes to specified review and legal procedures | Faster approval may create environmental trade-offs |
Together, these proposals reveal something that gets lost in much of the political discussion.
There is no single housing affordability problem.
There is a housing production problem, a land-use problem, a financing problem, and an income problem. In some communities, there is also an infrastructure problem.
Policies addressing one constraint may complement or complicate policies addressing another.
Helping people borrow more may expand purchasing opportunities. Building more homes may ease supply constraints. Streamlining approvals may reduce some development costs.
But the size and timing of those effects depend on conditions beyond the ballot measures themselves.
That is why claims that any one proposal will solve the housing crisis deserve careful examination.
<WritingBlock id=”58322″ variant=”document”>## Rhode Island: Borrowing to Create Housing, and the Cost of Public Investment
Rhode Island presents a more direct example of the relationship between housing development and public borrowing.
Question 2 would authorize $120 million in general-obligation bonds to support housing development and related activities.
The proposal includes financing for housing construction, acquisition, preparation of development sites, and programs designed to expand access to housing and homeownership.
At least $25 million would be devoted to expanding homeownership opportunities, while up to $10 million could support public housing development.
The idea behind the proposal is relatively straightforward.
Where the private market is not producing enough housing at prices affordable to certain households, public financing may help make additional projects possible.
That assistance might take the form of loans, grants or other financial support that reduces the costs faced by housing developers or eligible purchasers.
But financing is only one element of development.
A project still requires a suitable site, construction plans, approvals, contractors, labor, materials and ongoing operations.
If those elements are unavailable or excessively expensive, the amount of new housing generated by public borrowing can be lower than anticipated.
The distinction between a bond’s face value and its ultimate cost
The $120 million figure describes the principal amount Rhode Island would be authorized to borrow.
It does not include all borrowing costs.
Interest payments would increase the amount ultimately repaid, with estimates placing total principal and interest at approximately $192.5 million.
The existence of interest costs does not, by itself, establish whether the proposed investment is economically sound.
Governments routinely finance long-lived infrastructure and public assets over many years because their benefits may extend beyond the current generation of taxpayers.
The more useful questions concern the quality of the investment, the financing terms, the number of homes produced, and the durability of the resulting benefits.
A housing development that provides affordable homes for decades has a different financial profile from a temporary subsidy whose benefits expire after a short period.
The difficulty is that voters are usually asked to approve the financing before all the individual projects are completed.
That requires examining the proposed programs, fiscal estimates, accountability mechanisms and past performance of similar initiatives.
Rhode Island’s ballot raises a question relevant far beyond its borders: when housing is unaffordable, how much responsibility should the public sector assume for financing additional supply?
And if public borrowing is used, how should its results be measured?
Beyond Housing: Grocery Taxes, Income Taxes and the Price of Public Services
The ballot’s economic significance does not stop at the front door.
Middle-class affordability also depends on the cost of food, transportation, healthcare, education, utilities and the public services residents receive.
Several November measures concern those expenses directly or indirectly.
In Arizona, Proposition 316 would limit certain local grocery taxes, including restrictions on new or increased municipal taxes on food for home consumption.
Unlike many consumer taxes, grocery taxes apply to purchases that households cannot readily avoid.
That can make their impact especially noticeable for families devoting a relatively large share of income to necessities.
But sales taxes also provide revenue for municipal services. A restriction on those taxes can therefore create a fiscal issue for local governments depending on their existing tax structures.
The same trade-off appears in other parts of the country.
In California, Proposition 3 would extend an existing tax on higher incomes intended to support public education and healthcare. Other statewide proposals concern restrictions on certain taxes and how governments may raise or allocate revenue.
In Colorado, voters in some communities will consider measures involving property taxes, infrastructure borrowing, transit financing and local zoning authority.
For example, an increase in a municipal sales-tax rate might raise the cost of taxable purchases while also providing money for local services or infrastructure.
A school property-tax measure might increase costs for property owners while financing education programs, staffing or facilities.
The immediate financial effect and the longer-term community effect are not the same thing.
When a tax cut is not the whole financial story
Suppose a hypothetical household receives $900 in annual tax relief.
That is a real household benefit.
But imagine that the local government subsequently reduces a service the household uses, causing the family to spend an additional $500 annually on a private alternative.
Its net financial benefit would be smaller than the initial tax savings.
Now consider the opposite situation.
A community might raise a tax that costs the same family an additional $300 each year but finance a service that would otherwise cost the household substantially more.
Neither hypothetical proves the case for or against a particular ballot measure.
They simply illustrate why taxes and public services should be examined together.
The price of government is one part of household economics. The value and cost of the services financed by government are another.
Comparing different household-finance policies
| Policy approach | Possible direct household effect | Other consequences to examine |
|---|---|---|
| Property-tax exemption | Lower taxes for eligible owners | Local revenue changes and treatment of renters |
| Grocery-tax restriction | Lower or more predictable sales taxes on qualifying food | Municipal revenue and services |
| Housing construction bond | More financing for eligible housing projects | Debt service and actual housing production |
| Mortgage assistance | Improved financing access for qualifying buyers | Borrower repayment costs and housing demand |
| Zoning reform | More development possibilities | Infrastructure needs and construction response |
| School or transit tax | Higher applicable taxes | Public education, transportation and service benefits |
The important distinction is between money a household pays directly and the broader economic value or cost of a policy.
Both matter.
The Middle Class Is Not Experiencing the Housing Crisis in One Way
A recurring weakness in the national discussion of affordability is the assumption that middle-income Americans all face roughly the same financial circumstances.
They do not.
Consider four hypothetical households living in the same metropolitan area.
The first is a retired couple who bought a home thirty years ago. Their mortgage is paid off, but they live primarily on retirement income.
The second is a professional couple in their early thirties with steady employment and good credit. They have accumulated savings but cannot comfortably afford current home prices and mortgage payments.
The third is a family with two children renting a three-bedroom house. Their income has increased, but rent, childcare and transportation consume much of the additional money.
The fourth is an established homeowner with substantial equity who wants to downsize but finds that buying a smaller property would not necessarily produce much financial relief.
All four could reasonably be described as middle class.
Yet their exposure to property taxes, zoning, mortgage financing and housing costs is different.
A larger homestead exemption may provide immediate relief to the retired couple.
It may do little for the younger couple until they become homeowners.
A mortgage financing program may provide the younger couple with an additional purchasing option, subject to eligibility, without improving the retired couple’s finances.
A zoning reform that permits smaller homes could potentially create more suitable properties for the younger buyers and the older downsizers.
The renting family might benefit from an expansion of rental supply or access to affordable-housing programs, but may receive no direct savings from a homeowner-only tax exemption.
These differences are not reasons to dismiss any particular policy.
They are reasons to be precise about who qualifies, what costs change, and which benefits are direct rather than speculative.
How different households may experience the same policy
| Household | Potential benefit | Limitation or uncertainty |
|---|---|---|
| Longtime homeowner | Property-tax exemptions and assessment protections | Does not necessarily reduce insurance or maintenance |
| First-time homebuyer | Mortgage assistance and more starter-home supply | Purchase prices and ongoing costs may remain high |
| Renter | Increased rental supply or affordable housing programs | Homeowner tax relief may not directly reach renters |
| Retiree considering downsizing | More housing choices and potentially lower carrying costs | Moving may reset assessments or introduce financing costs |
| Small-business owner | Workforce housing and improved access to employees | Tax and infrastructure changes may alter operating costs |
For Financial Middle Class, this distinction is especially relevant.
Financial security is not determined solely by annual income.
It also depends on household assets, debt obligations, family responsibilities, housing tenure, geography and the relationship between recurring expenses and disposable income.
A household earning $100,000 in an expensive metropolitan area may face very different choices from a household earning the same amount in a lower-cost region.
And two households with identical incomes can have dramatically different financial positions if one owns a home purchased fifteen years ago and the other must purchase at today’s prices and financing terms.
This is why broad references to helping the middle class should be evaluated against the specific design of a proposal.
The Most Important Housing Distinction: Reducing Costs Versus Increasing Supply
If there is one economic idea worth taking away from the 2026 ballot, it is this:
Making housing less expensive for a particular household is not always the same as making housing more abundant.
Property-tax reductions lower selected ownership expenses.
Mortgage assistance changes financing options.
Housing bonds provide capital for development programs.
Zoning reform changes what builders may construct.
Each works through a different economic channel.
Consider two hypothetical communities.
In Community A, available housing is scarce, and the local government creates a program that helps eligible buyers borrow additional funds.
Some buyers may gain access to homes they could not otherwise finance.
However, if the number of homes for sale remains fixed, those buyers are still competing over the same limited supply.
In Community B, changes in development rules allow more homes to be constructed. Over time, an increase in available housing could moderate price pressure relative to what otherwise would have occurred.
That does not guarantee homes will become inexpensive. But it changes the supply side of the market.
The distinction matters because affordability depends partly on the relationship between housing demand and housing availability.
Financing programs can help address barriers that prevent households from purchasing homes.
Construction and land-use reforms may help address barriers that prevent homes from being produced.
In some circumstances, the two approaches may complement one another.
In others, the timing or design of the policies may create new complications.
It is also important to recognize that homeowners do not necessarily share the same economic incentives as prospective buyers.
A substantial increase in the number of homes available for sale could help aspiring purchasers by moderating price pressure.
Existing homeowners might view slower appreciation differently, particularly if much of their wealth is tied to their property.
That tension lies near the center of American housing policy.
Housing is both a necessity and an investment.
The policies that make it more accessible as a necessity do not always maximize its value as an investment.
A durable affordability strategy must confront that contradiction rather than pretend it does not exist.
The Hidden Cost of Housing: Infrastructure and Local Government Finance
A house does not function in isolation.
It depends on roads, water systems, drainage, emergency services, schools, utilities and other infrastructure.
When communities grow, demand for those services often increases.
That infrastructure can be expensive to build, maintain and eventually replace.
This is why debates about housing construction and property taxation are more closely connected than they initially appear.
A community that permits additional housing may need to finance infrastructure improvements.
The same community might also receive additional property-tax revenue and economic activity from new development.
Whether the new revenue covers the resulting costs depends on development patterns, service needs, existing infrastructure capacity and the local financing system.
Likewise, a community that sharply reduces property-tax revenue may face difficult decisions about maintaining or expanding public services.
Those decisions can influence the long-term attractiveness and affordability of living there.
A lower annual tax bill may make a home easier to carry.
But households may also consider commute times, school conditions, public safety, water reliability and the overall functioning of the community.
Public services are not free, but neither is their absence.
For voters, the relevant financial question is not simply how much government spends.
It is what households receive, what alternatives would cost, and whether the financing arrangement is sustainable.
How to Interpret a Ballot Measure Without Getting Lost in the Language
Ballot language can be unusually difficult to interpret.
A measure may be written as a constitutional amendment, a statutory change, a bond authorization or a restriction on future government authority.
The title may be brief even when the legal text is extensive.
And an appealing objective does not necessarily reveal the details of implementation.
The most useful approach is to begin with the proposed legal change and then consider its economic consequences.
For example, a measure that authorizes borrowing does not necessarily require every dollar to be spent immediately.
A proposal that expands an exemption may have different effects depending on how exemptions are calculated and which taxes remain applicable.
A zoning measure may change development rights without eliminating building codes or infrastructure requirements.
And a constitutional restriction may limit future policy choices without changing a household’s current bill.
What selected Yes and No votes would mean
| Measure | Yes would | No would |
|---|---|---|
| Florida Amendment 3 | Adopt the proposed homestead exemption changes | Leave the proposed expansion unenacted |
| Massachusetts Question 7 | Permit qualifying single-family homes on smaller lots, subject to specified regulation | Leave current statewide law unchanged by this proposal |
| California Proposition 1 | Authorize the specified housing bonds | Decline the new bond authorization |
| California Proposition 37 | Establish the proposed qualifying buyer loan program | Leave the proposed program unauthorized |
| California Proposition 45 | Adopt the specified environmental review changes | Retain existing law rather than enact those changes |
| Rhode Island Question 2 | Authorize the proposed housing bonds | Decline the new borrowing authorization |
| North Carolina property-tax amendment | Require the legislature to establish property-tax levy limits | Leave out the proposed constitutional requirement |
The comparison tells voters what a measure would legally authorize or change. It does not predict the full economic effect of implementation.
Five questions that help explain the financial stakes
When examining any ballot measure, the first question is who receives the benefit.
An exemption restricted to primary residences is different from a tax reduction applying to every property. A mortgage assistance program limited by income and purchase price will reach a different population from a program open to all homebuyers.
The second question is who ultimately pays.
If a program requires new borrowing, future repayment obligations matter. If a proposal reduces tax collections, the effect on public revenues matters. If a change shifts expenses from government to households, that cost should also be considered.
The third question concerns what the proposal will actually produce.
For a housing bond, that might mean completed homes, units preserved, or eligible households assisted. For a zoning proposal, it might mean permits issued, new construction and changes in housing availability.
The fourth question is how long those results may take.
A tax exemption might affect a future tax bill relatively quickly. A housing development can take years to complete.
Finally, voters can consider what happens if the policy does not work as anticipated.
Can officials adjust the program? Are there accountability provisions? Are there legal restrictions preventing later changes? How will results be measured?
These questions do not supply a predetermined voting decision. They provide a way to distinguish the stated purpose of a proposal from its design and possible consequences.
What Happens After November 3?
Election night is only the beginning of the policy process.
Some ballot measures establish changes that take effect on specified dates. Others require legislation, regulations, administrative programs or funding decisions before their effects can be fully realized.
For example, approving a constitutional direction to limit tax levies may still leave lawmakers responsible for deciding how the limits operate.
A housing bond authorization may require agencies to select projects, distribute financing and oversee construction.
A development reform may need administrative guidance and could face legal interpretation disputes.
Even an approved property-tax exemption must be implemented through assessment and billing systems.
The practical financial consequences may therefore unfold over several years.
For readers following these issues after the election, a useful measurement of success will be whether the stated goals translate into observable outcomes.
Did eligible homeowners receive the anticipated savings?
Did additional housing actually get built?
Did mortgage assistance reach the households identified in the proposal?
Did local revenue changes affect public services or taxes elsewhere?
Those are measurable questions, although the answers may require time and careful analysis.
The Bigger Question: What Does an Affordable Middle-Class Life Look Like?
For much of the twentieth century, a central feature of the American middle-class experience was the possibility of converting steady employment into lasting financial security.
A household did not necessarily need extraordinary wealth.
It needed income sufficient to cover necessities, some money left over for savings, and a realistic chance to purchase a home without sacrificing everything else.
Homeownership became one of the most important ways families built assets.
But the economic arrangement behind that expectation has become harder to sustain in many communities.
For households that already own property, rising values have generated wealth on paper while increasing some of the costs associated with keeping a home.
For households still trying to buy, those higher values can represent an increasingly difficult barrier to entry.
State and local governments face their own version of the same challenge.
Residents want affordable housing and manageable taxes. They also expect functioning infrastructure, schools, emergency services and other public responsibilities to be financed.
Developers face costs associated with land, labor, materials, financing and regulations. Buyers face mortgage rates, down payments and ongoing expenses. Renters face competing demands on limited housing supply.
No single group controls all those variables.
And no single ballot measure can resolve every part of the problem.
The November 3 election offers several different policy approaches.
Florida’s proposal concentrates on the carrying costs of existing homes.
Massachusetts addresses restrictions on the creation of smaller homes.
California examines public investment, buyer financing and development review.
Rhode Island considers borrowing to expand housing programs.
Other states are rethinking property assessments, tax authority and the financing of public services.
Taken together, these measures provide a useful window into the financial pressures facing American households.
They also demonstrate that affordability involves choices.
Lower taxes can increase disposable income while changing public revenues.
More development can expand housing opportunities while raising infrastructure questions.
Public financing can make additional housing possible while creating repayment commitments.
Mortgage assistance can improve access while leaving underlying price and supply challenges unresolved.
These are not contradictions that disappear through political messaging.
They are economic trade-offs that deserve to be understood.
And perhaps that is the most important lesson of the 2026 ballot.
The financial future of the American middle class will not be determined only by decisions made in Washington.
It will also be shaped by decisions about land, housing, taxation and public investment made much closer to home.
For households trying to preserve what they have built, or hoping to build something of their own, those decisions can matter for years.
The question is not merely whether a community can make housing cheaper today. It is whether the policies governing that community can support an affordable, financially sustainable middle-class life tomorrow.
Sources and further reading
This article draws on election materials and reporting available as of October 15, 2026. Official ballot texts and fiscal analyses take precedence over campaign descriptions.
- National Conference of State Legislatures — The Tax Measures Voters Will See on Their November Ballots
- NCSL — Statewide Ballot Measures Database
- Massachusetts Secretary of the Commonwealth — Question 7
- California Secretary of State — Official Proposition Guide
- California Secretary of State — Proposition 1 Fiscal Analysis
- North Carolina General Assembly — Property Tax Levy Limit Amendment
- Florida Division of Elections — Official Voter Resources
Editor’s note: Illustrative households, financial examples and simplified tax calculations are explanatory, not forecasts or personalized financial advice. Readers should consult their official state and local voter guides for the complete wording and fiscal analysis of measures appearing on their ballots.


RELATED ARTICLES
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover how new rules from federal housing regulators could affect mortgage approvals, borrowing costs, and financial opportunities for American homebuyers—and why a higher credit score doesn't...
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what something actually costs. From buy now, pay later services to longer auto loans and installment financing, businesses are making expensive purchases appear more manageable by...
Leave Comment
Cancel reply
Gig Economy
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From Florida's homestead exemptions to Massachusetts zoning reform and California's affordable housing...
By Article Posted by Staff Contributor
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover how new rules from federal housing regulators could affect mortgage approvals,...
By Article Posted by Staff Contributor
American Middle Class / Oct 13, 2026
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what something actually costs. From buy now, pay later services to longer...
By Article Posted by Staff Contributor
American Middle Class / Oct 12, 2026
Fair Capitalism: We Don’t Need to Abolish Capitalism. We Need to Fix It.
Fair capitalism means preserving entrepreneurship and profits while ensuring working Americans share more meaningfully in the prosperity they help create.
By MacKenzy Pierre
American Middle Class / Oct 12, 2026
The Sunday Scaries: How Financial Independence Can Help You Reclaim Your Weekend
The Sunday Scaries can begin long before Monday morning. Building emergency savings, lowering monthly expenses, and increasing financial independence may help you reclaim your weekend.
By Article Posted by Staff Contributor
Business / Aug 08, 2026
The Missing Middle in Black Entrepreneurship
Black entrepreneurship has expanded dramatically. The next challenge is helping more Black-owned businesses move from self-employment to employer firms and sustainable scale.
By FMC Editorial Team
Personal Finance / Aug 01, 2026
Cash Strategy: Put Every Dollar in the Right Place
Your checking account, emergency fund, short-term savings, and investments should not be managed the same way. This cash strategy helps assign every dollar to the right...
By Article Posted by Staff Contributor
Personal Finance / Aug 01, 2026
Best HYSA: How to Choose Beyond the Highest APY
A competitive interest rate matters, but it is only one part of choosing a high-yield savings account. Compare insurance, fees, access, transfer speed, and promotional conditions.
By Article Posted by Staff Contributor
Personal Finance / Aug 01, 2026
High-Yield Savings vs. CDs, Treasury Bills, and Other Safe Places for Cash
High-yield savings accounts are excellent for accessible cash, but they are not always the best choice. Compare HYSAs, CDs, Treasury bills, money market accounts, and I...
By Article Posted by Staff Contributor
American Middle Class / Aug 01, 2026
High-Yield Savings Accounts: A Safer Home for Your Cash
A high-yield savings account can pay several times the national savings rate while keeping qualified deposits federally insured. Here is how it works, what to watch...
By Article Posted by Staff Contributor
Latest Reviews
American Middle Class / Oct 16, 2026
The American Middle Class’s Guide to the 2026 Midterm Ballot Measures
The 2026 midterm elections will put major housing and tax proposals before American voters. From...
Personal Finance / Oct 14, 2026
FICO Finally Has Competition. Will Homebuyers Get a Better Deal?
For decades, FICO dominated mortgage credit scoring. Now VantageScore 4.0 is challenging that dominance. Discover...
American Middle Class / Oct 13, 2026
Selling Affordability Through Installments
Americans are increasingly buying based on what they can afford each month rather than what...